 By Rene Philippe Raymond Dubout · · Updated
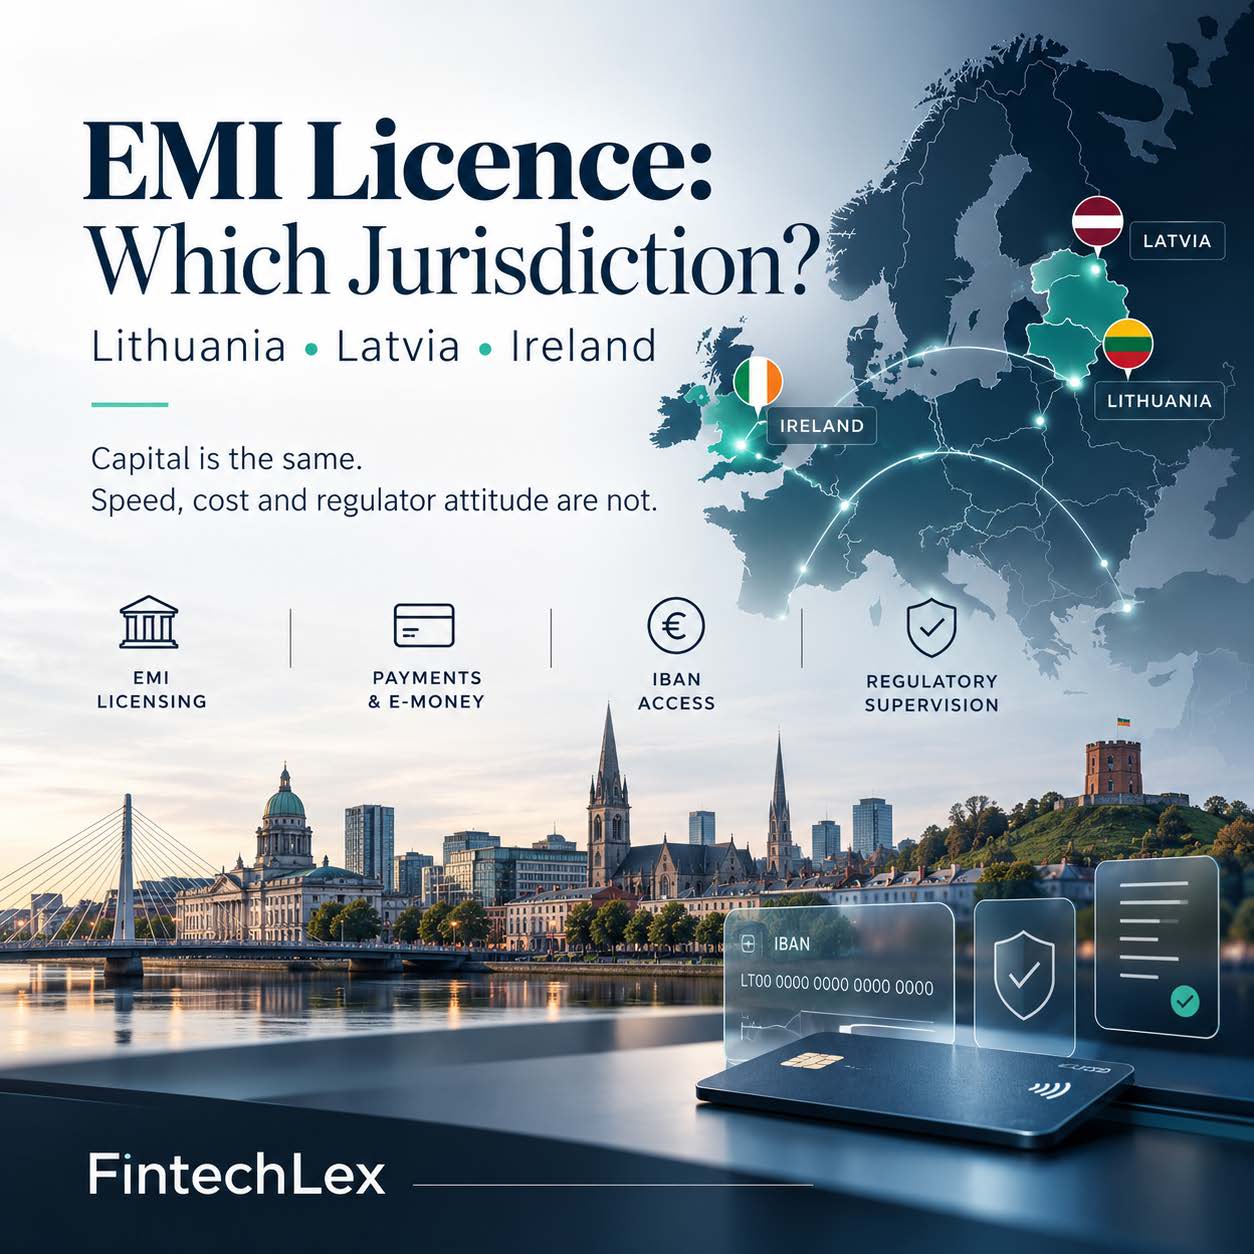
An electronic money institution (EMI) licence lets you issue e-money, hold client funds, open IBAN accounts, run payments and, with a card scheme membership, issue cards – across the whole EEA through passporting. The capital requirement is the same everywhere: EUR 350,000. What differs is speed, the regulator’s attitude and the real cost of getting there. Here is the honest comparison, and when buying an existing EMI is the better route.
Ask us which route fits your project.
A map that keeps moving
When Rene-Philippe started in this business in 2012, the destination was Bulgaria: low operating costs, and licences that were relatively easy to obtain. Then Bulgaria became more difficult, and the market moved to Lithuania.
At the time, Estonia and Latvia were also easy places to get a licence. But both had serious money-laundering problems, with banks collapsing, and we would not touch them with a bargepole.
Today the picture has changed again. The Bank of Lithuania has become much stricter: a licence that used to take four to five months now takes twelve to fourteen. Meanwhile, Latvia and Estonia have cleaned up their act and are workable again, and Slovakia has become a serious option.
The lesson: the best jurisdiction never stays the best for long. Choose on today’s facts, not on yesterday’s reputation.
The three main jurisdictions
| Lithuania | Latvia | Ireland | |
|---|---|---|---|
| Regulator | Bank of Lithuania | Latvijas Banka (single supervisor since 2023) | Central Bank of Ireland |
| Initial capital | EUR 350,000 | EUR 350,000 | EUR 350,000 |
| Realistic timeline | 12–14 months (it used to be 4–5) | 7–10 months (3-month legal clock) | 9–14 months |
| Year-one budget, capital included | EUR 250,000–450,000 | About EUR 400,000–465,000 | EUR 350,000–600,000+ |
| Character | The EU’s largest EMI hub, now selective | Smaller, less crowded; direct access to the central bank’s EKS payment system | Demanding, with long experience of high-risk and gambling models |
Timelines and budgets as quoted by licensing advisers in 2026; the real figure depends on your business model and the quality of the file.
Lithuania: the hub that closed the door a little
Lithuania became Europe’s EMI capital with a fast, English-language process. It is now much more selective, and much slower: count twelve to fourteen months. In 2024 the Bank of Lithuania granted only three new EMI and payment institution licences, revoked nine, and authorised twelve acquisitions of existing institutions. Read that again: four times more people entered the Lithuanian market by buying than by applying.
Latvia: the quieter alternative
Since 2023, Latvijas Banka is the single regulator. The process is smaller and less crowded than in Lithuania, and a Latvian EMI can connect directly to the central bank’s EKS system for SEPA payments, which can make transfers dramatically cheaper. Corporate tax is 0% on retained profits.
Ireland: the route for high-risk models
The Central Bank of Ireland is respected by banks and partners, and an Irish EMI opens doors. It is also slow and demanding: plan for more than nine months and a strong local team. But Ireland is above all the jurisdiction for EMIs with particular profiles: high-risk models and gambling. The Central Bank has long experience with them, which is why we often recommend it for those clients. For more detail, see our Ireland EMI guide.
Two more routes: France and Liechtenstein
Lithuania, Latvia and Ireland get most of the attention. Two other jurisdictions deserve a serious look, for very different reasons: France for its weight, Liechtenstein for its size.
France: heavyweight, French-speaking, and slower than advertised
A French EMI is authorised by the Autorité de contrôle prudentiel et de résolution (ACPR), part of the Banque de France. The capital is the same as everywhere, EUR 350,000. What you buy with a French licence is weight: banks, card schemes and partners take an ACPR-authorised institution seriously, and France is the largest market you can serve from home rather than through a passport.
The price is substance and language. The ACPR expects at least two effective managers who actually run the institution from France, real local staff, and a compliance officer it knows by name. The main file is in French, and so is the documentation for retail clients. A Paris mailbox and a team in Vilnius will not do.
A few years ago, we and others advertised “EMI Express” packages promising a French licence in four to six months. Be careful with such promises. The ACPR has three months to decide once the file is complete, but getting the file to “complete” is the long part; in practice, count nine to fifteen months. We also used to present France as the friendly home for EMIs serving crypto businesses. Since the MiCA regulation, crypto services need their own licence from the Autorité des marchés financiers, and whether an EMI accepts crypto clients depends on its own risk policy, wherever it is licensed.
France makes sense when your market is French, your team can work in French, and you want a licence that impresses banks. It makes little sense as a shortcut.
Liechtenstein: small, EEA, and Swiss in its plumbing
Liechtenstein is in the European Economic Area, so an EMI authorised by its Financial Market Authority (FMA) can passport across the EU like any other. But the country uses the Swiss franc and sits in a customs union with Switzerland, so its financial institutions live close to the Swiss payment system and Swiss banks. For a project that wants an EU passport and a Swiss neighbourhood, that combination is unique.
The FMA’s own guidance is precise about what it expects:
- Capital: at least EUR 350,000, or the equivalent in Swiss francs.
- Executive board: at least two members, together working at least the equivalent of two full-time positions, and not sitting on the board of directors.
- Board of directors: at least three members.
- Presence: registered office and head office in Liechtenstein, and the company must already exist when you apply.
- Language: the application and the business plan must be in German; other documents may be in English after consulting the FMA.
- Time: the FMA must decide within three months of a complete application.
In other words, Liechtenstein is not a cheap jurisdiction: five senior people before your first client, an office in Vaduz and German-language paperwork. In exchange, you deal with a small regulator that answers the phone, in a country with a strong financial reputation. Our 2021 post called it the best place to get an EMI licence. We would now say: one of the best for the right project, and an expensive mistake for the wrong one.
Other jurisdictions worth a look
- Slovakia. A good jurisdiction to work with. The National Bank of Slovakia offers its own access to SEPA payments, at an even lower cost than Lithuania’s CENTROlink.
- Estonia. Back on the map after cleaning up its money-laundering problems.
PSD3: the licence is about to change
The EU reached political agreement on the new Payment Services Directive (PSD3) and Payment Services Regulation in November 2025, and the final texts were published in April 2026. They are expected to apply around 2028. The E-Money Directive is repealed and EMIs become a category of payment institution. Existing EMIs will have a transition period to show they meet the new standards, or re-apply.
In practice: an EMI licensed today, or bought today, will have to be brought up to PSD3 standards within a few years. Factor that into your budget and into the due diligence on any EMI you buy.
Apply or buy?
Buying an existing EMI is not automatically faster. The new owner still needs the regulator’s approval of the change of control, which takes months, and a premium is paid on top of the EUR 350,000 capital. A licence with no technology, no banking relationships and no clients is rarely worth that premium.
Buying makes sense when the EMI brings what money cannot buy quickly:
- Its own technology: core banking, KYC and transaction monitoring, client portal.
- Payment access: SEPA through a bank or, better, directly through the central bank.
- A card scheme membership, such as Visa principal membership, which takes long to obtain.
- Banking relationships and a clean compliance record.
- Clients and revenue, even modest ones.
We currently have an EU EMI available: see our Lithuanian EMI for sale, and ask us for new opportunities, which come regularly. Prices on request: insight@fintechlex.com.
Which route for which project?
- You need to be live in months, with cards and SEPA: buy an operating EMI with real assets.
- Your model is high-risk, such as gambling: apply in Ireland.
- You want a lean EU base with low payment costs: apply in Latvia or Slovakia, or buy there.
- Your market is France and your team works in French: apply in France.
- You want an EU passport with a Swiss neighbourhood: look at Liechtenstein.
- You only need accounts and cards for your clients: you may not need a licence at all – see white-label banking and neobank solutions.
- Your clients are outside the EU: compare with a Swiss structure – European EMI vs Swiss fintech licence.
We help you choose, then execute: EMI applications, EMI acquisitions and the change-of-control file. Write to insight@fintechlex.com.
Sources: ACPR, authorisation of payment and e-money institutions; FMA Liechtenstein, Guidance 2018/18 on the licence as an e-money institution (E-Money Act of 17 March 2011); Regulation (EU) 2023/1114 (MiCA); Bank of Lithuania, Latvijas Banka and Central Bank of Ireland public registers and statistics.
This article is for general information only and does not constitute legal advice.