Banks for sale come in two kinds: the licence nobody uses, and the bank somebody actually runs. This one is the second kind.
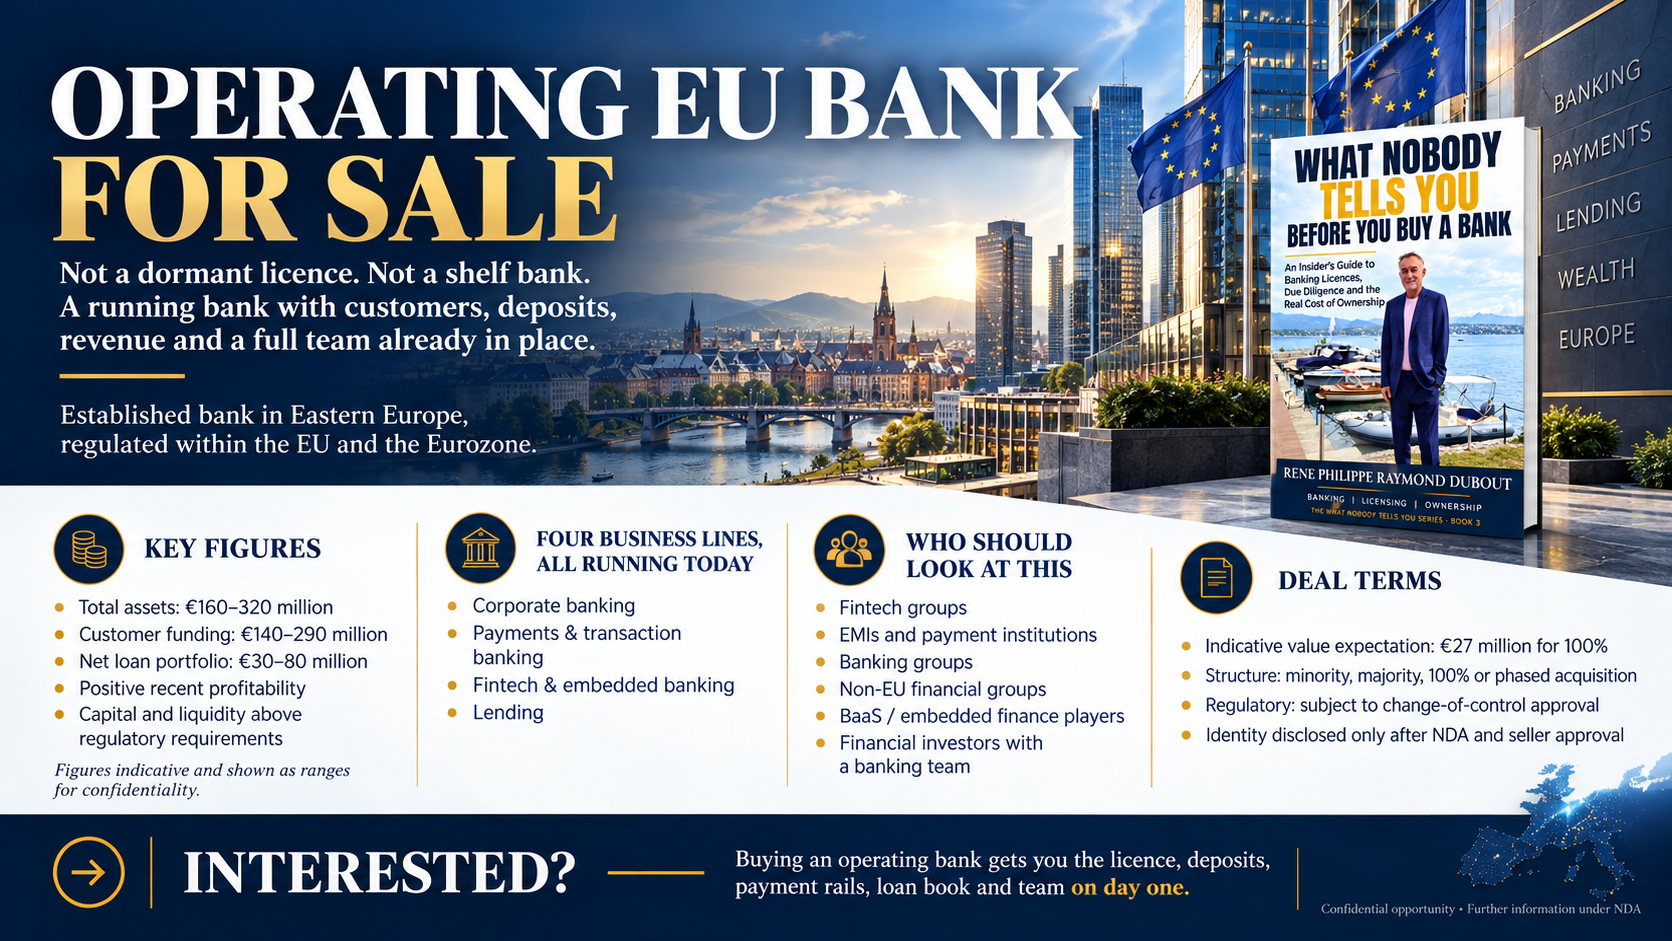
We are presenting an established, operating bank in Eastern Europe, regulated within the EU and the Eurozone. It combines corporate banking, payments, lending and fintech-oriented services, with customers, deposits, revenue and a full team already in place. Not a dormant licence or a shelf bank, or an application waiting for a regulator to wake up a real operating bank.
Key figures
- Total assets: €160–320 million
- Customer funding: €140–290 million, predominantly customer deposits
- Net loan portfolio: €30–80 million, with positive recent development
- Fee and commission income: a meaningful share of operating revenue
- Profitability: positive in the recent period
- Capital and liquidity: above applicable regulatory requirements, with a substantial liquidity position
Figures are indicative and shown as ranges for confidentiality.
Four business lines, all running today
- Corporate banking: corporate and SME accounts, domestic and international payments, treasury and FX where supported.
- Payments and transaction banking: European payment connectivity, SEPA, international payments, settlement.
- Fintech and embedded banking: servicing financial institutions and fintechs, with integration capability for institutional clients.
- Lending: a business-oriented loan book with underwriting and servicing in-house.
This is not a bank living on its interest margin alone. Fees and commissions carry a real part of the revenue.
Who should look at this
- Fintech groups that want their own bank instead of renting someone else’s
- EMIs and payment institutions ready to move up to a full banking licence
- Banking groups looking for a further EU platform
- Non-EU financial groups that want a foothold in the EU and the Eurozone
- Banking-as-a-service and embedded-finance players that need a regulated balance sheet
- Financial investors with a banking team able to run and grow it
Deal terms
- Indicative value expectation: €27 million for 100% of the bank
- Structure: minority, majority, 100% or phased acquisition
- Regulatory: subject to change-of-control approval by the competent supervisor
- Confidentiality: the bank’s identity is disclosed only after an NDA and the seller’s approval of the buyer
Why buy rather than build?
Building a bank means years of licensing, capital burnt before the first client, and a team you have to hire one by one. Buying an operating bank gets you the licence, the deposits, the payment rails, the loan book and the people on day one. You still need the regulator’s blessing for the change of control. But you are not starting from an empty office.
Interested?
Serious, well-capitalised parties only. Write to us at insight@fintechlex.com with a short presentation of your group and your acquisition rationale, and we will send the NDA.
Before you buy a bank, read what nobody tells you
Most people who buy a bank find out the hard way what they should have asked before signing. I wrote What Nobody Tells You Before You Buy a Bank so you can find out the cheap way. It covers what to check before you buy or build a bank, the offshore banking jurisdictions, and Europe’s microstates, with a decision table at the end of every chapter. No theory for bankers: practical answers for investors who want a bank and don’t want surprises.
Available on Amazon, Apple Books and Google Play: see all my books.