
From Advising Investments to Building Them
For thirty years, investors came to us with projects and asked us to make them work.
Now we build our own.
Since 1995, we have structured and executed foreign direct investment projects across Thailand, Myanmar and Cambodia, and from our Geneva base into Switzerland and Europe.
Manufacturing. Real estate. Infrastructure. Telecommunications. Hospitality. Financial services.
Our role was never limited to legal advice.
We handled the licences, contracts, due diligence, regulatory approvals and transaction structure — and stayed involved through execution and, where relevant, through to exit.
On the regulatory side, our work has included Swiss SRO membership, FINMA licensing, banking matters, and fintech authorisations across Switzerland, the European Union and the United Kingdom.
Over time, this created two capabilities that rarely sit under one roof: the ability to execute a project on the ground in Asia, and the ability to structure it into a compliant, investable vehicle in Switzerland.
Today, we apply thirty years of that experience to projects we originate ourselves.
We identify the sector.
We develop the concept.
We test the commercial case.
We analyse the regulatory framework.
We build the operating model.
We structure the investment vehicle.
Only then do we raise capital.
For an investor, this changes what arrives on the table.
Not an idea on a slide, but a project that has already been subjected to the same commercial, legal, regulatory and operational discipline that we applied to other people’s investments for three decades.
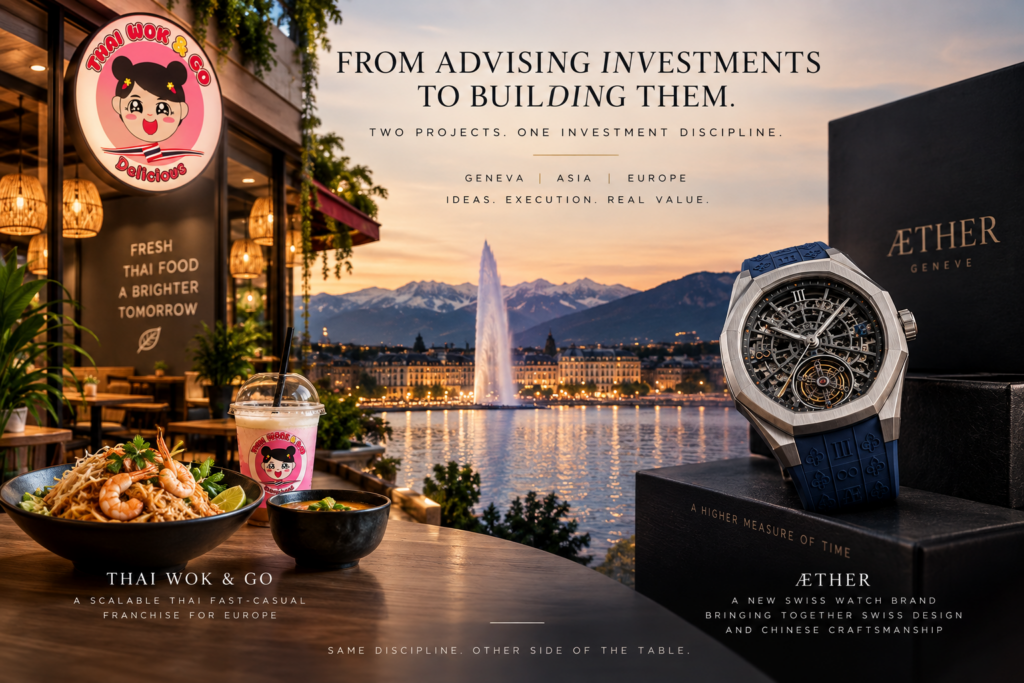
Our First Project: A Scalable Thai Fast-Casual Concept
Our first project is a Thai fast-casual restaurant concept designed to scale from Geneva across Europe.
Switzerland has a substantial Thai restaurant market, yet no established branded Thai fast-casual chain of meaningful scale.
We identified the gap, carried out the market study, developed the concept and business plan, and secured the operating team.
The initial rollout envisages 10 locations over two years, comprising four larger restaurant-format units and six smaller takeaway-led units with limited seating.
The total funding requirement is approximately CHF 3.5 million.
Year 1 is expected to be primarily a build-out and break-even period, with the priority being to establish the network and operating platform rather than generate significant investor returns.
The economics become more attractive from Year 2, once the initial 10 units are operating and centralised purchasing and supply margins begin contributing materially.
From Year 3, the model is designed to benefit not only from the profitability of the initial corporate locations, but also from additional revenue streams including franchise fees, recurring margins on franchisee purchasing and other network income.
The objective is not simply to operate ten restaurants.
It is to build the platform for a scalable European franchise.
Our Second Project: ÆTHER
Our second project is ÆTHER, a new watch brand built around what Switzerland and China each do best. Swiss design, Swiss quality control and Swiss after-sales service on one side. On the other hand specialist Chinese mechanical watchmaking expertise
The result is a proposition designed to make a genuine mechanical tourbillon accessible at a price point of CHF 2’999, while supporting the product with a ten-year Swiss warranty backed by a dedicated reserve.
The financing has been deliberately structured in stages.
The first CHF 300’000 funds the proof of concept. It finances the first 33 watches, places the tooling in ÆTHER’s name and secures the core intellectual property and trademarks.
A second call of CHF 650’000 funds the launch of the Geneva boutique and an initial inventory of 195 watches.
Together, these first two stages represent CHF 950’000 of capital.
A final call of CHF 1.55 million would only be released once the boutique is trading and the commercial model has been demonstrated.
That capital funds production working capital, twelve months of operating runway and a dedicated warranty reserve.
The structure is designed so that later capital scales a functioning business rather than funding the initial proof of whether the concept works.
Importantly, approximately CHF 500’000 remains unallocated as contingency. It gives the business the capacity to absorb slower-than-planned sales, higher costs or other execution risks without additional funding.
On the current financial model, operational break-even is reached at approximately 246 watches in the first full year of sales — around 21 watches per month.
Two Projects. One Investment Discipline.
The sectors are different.
The methodology is not.
In each case, we identify the opportunity, develop the commercial model. Then we test the regulatory and operational assumptions, structure the investment and build the execution platform.
That is the transition we are making.
From adviser to originator.
Same discipline. Other side of the table.
Both projects are now ready to be presented to selected investors.
For investors who would like to review the projects in greater detail, we would be pleased to provide the full White Paper and financial materials for either opportunity.
Please contact us to request the White Paper or arrange a confidential discussion