 By Rene Philippe Raymond Dubout · · Updated
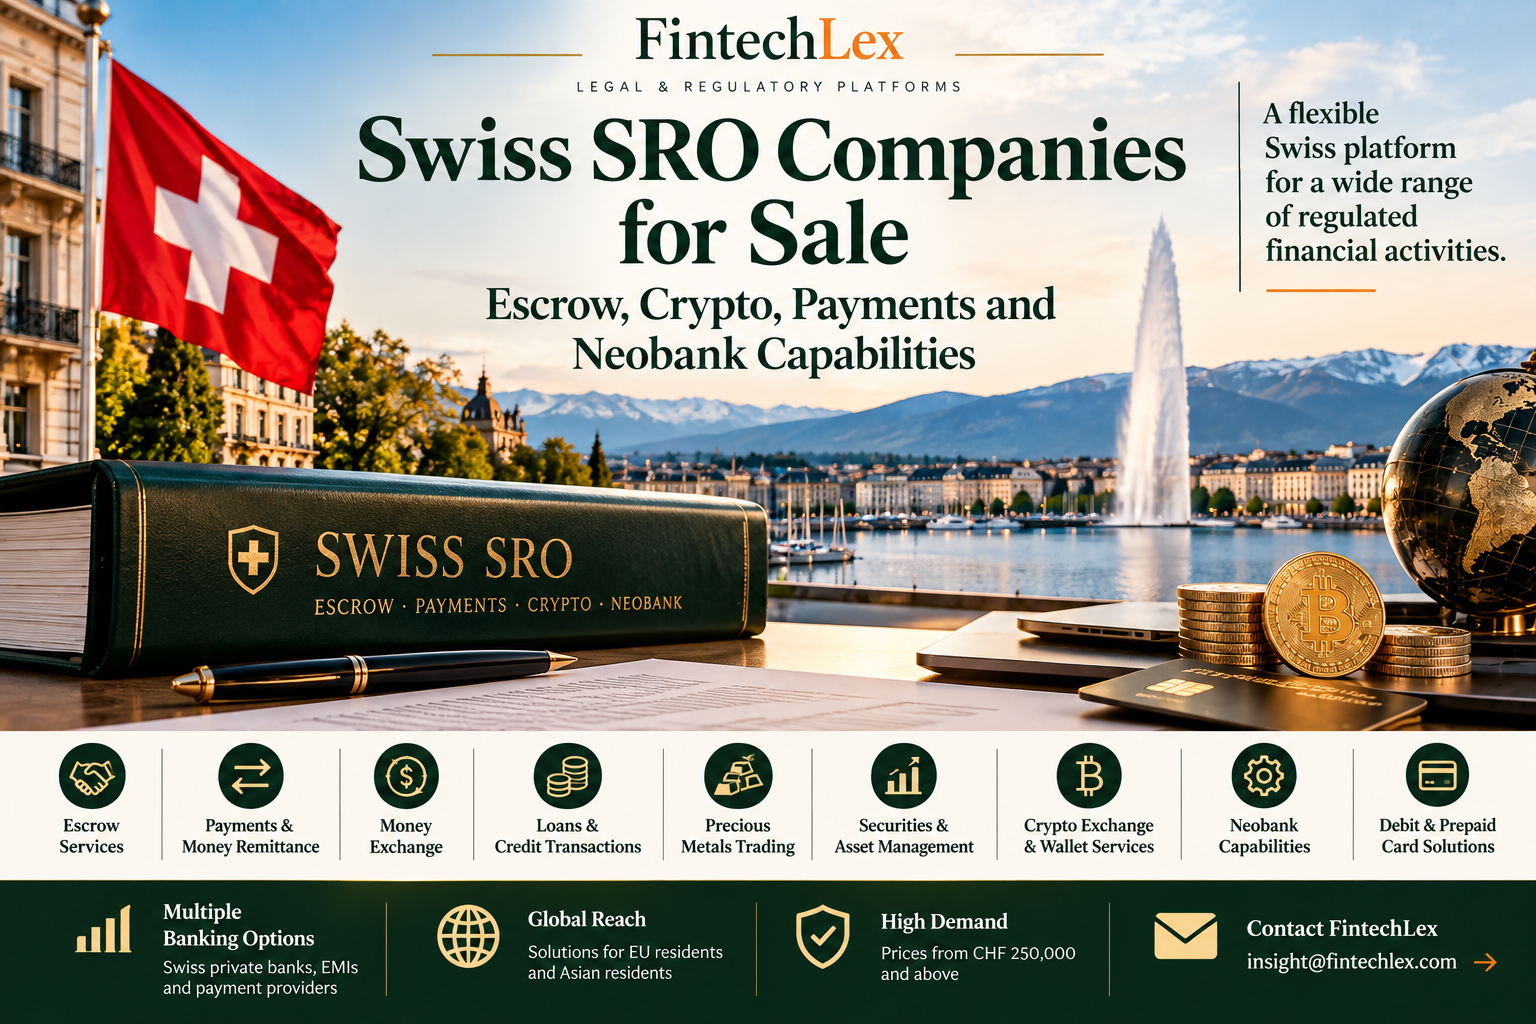
Swiss SRO Companies for Sale — Escrow, Crypto, Payments and Neobank Capabilities FintechLex always has access to Swiss companies suitable for escrow and regulated financial activities.
We do not publish names or prices: good structures tend to sell quickly, and availability changes constantly. The companies currently with us are listed below, anonymised.
What matters is therefore less the name of the company available today than what these Swiss structures can actually be used for — and the banking and payment infrastructure that can be built around them.
Currently available
| Company A | Company B | |
|---|---|---|
| Legal form | Swiss AG | Swiss AG |
| Founded | 1980s | 2018 |
| Regulation | Member of a Swiss SRO, with a crypto (VASP) profile | Member of a Swiss SRO, with a crypto (VASP) profile |
| AML audit | Clean audit for 2025 | Compliant every year since 2021 |
| Activity | Currently dormant | Broad payments and crypto purpose |
Names, audit reports and terms are shared with qualified buyers after a first call and a confidentiality agreement. Ask us for the details.
What can a Swiss SRO structure do?
Depending on the company, its existing registrations and the final business model, a Swiss SRO-regulated structure can be used for a surprisingly broad range of financial activities.
Typical activities can include:
- Escrow services
- Money remittance and payment transactions
- Foreign-exchange operations
- Credit and loan transactions
- Precious-metals trading
- Securities-related activities
- Asset management within the applicable Swiss regulatory limits
- Crypto exchange
- Crypto wallets
- Custodial and non-custodial wallet services
- Online and offline staking services
- Crypto and fiat payment solutions
- Merchant payment solutions
- Crypto-asset-backed lending
- Staking-backed lending
- Crypto-related advisory services
Note for buyers: under the reform of the Financial Institutions Act in consultation, crypto exchange, custody and trading for clients are expected to need the new FINMA crypto institution licence, and holding client funds could need the new payment instrument institution licence. Existing SRO companies would get one year to apply and could continue until FINMA decides. The value of an SRO company therefore depends on what it does.
Client funds may also be held in connection with a specific transaction, for example an acquisition of precious metals or crypto assets, subject to the applicable Swiss regulatory framework and the permitted holding period.
Escrow banking is the key
The company itself is only part of the solution.
A serious escrow business also needs the right banking infrastructure, and this is an area where FintechLex can provide several alternatives.
Depending on the business model and client profile, we can arrange solutions including:
Swiss private bank solution 1
An operating account together with a dedicated account for providing escrow services.
Swiss private bank solution 2
An operating account together with banking infrastructure suitable for certain crypto-related transactions.
For this second solution, transactions are generally intended for amounts above €500,000, making it particularly relevant to businesses servicing HNW and UHNW clients undertaking substantial crypto transactions.
Additional solutions can also be considered through:
- Other Swiss banks
- European EMIs
- Swiss payment companies
- Other regulated payment partners
This means that the banking structure can be adapted to the actual business rather than trying to force every client into the same solution.
Building a neobank around the structure
A Swiss SRO company can also form part of a broader neobank or fintech structure.
Through suitable white-label partnerships with licensed EMIs or other regulated providers, additional capabilities may be integrated, including:
- Payment accounts
- Cash-in and withdrawal functionality
- Payment execution
- Payment transactions linked to credit facilities
- Money transfers
- Issuing and acquiring payment instruments
- Electronic-money functionality
- Debit cards
- Prepaid cards
Card programmes can be arranged for European residents, Asian residents or both, although the appropriate card issuer and programme will depend on the residence of the end customers.
In other words, you do not necessarily need to obtain a banking licence or EMI licence yourself to build a neobank. The regulated activities that require such a licence can be provided through an appropriately licensed white-label partner.
Financial advisory can also be added
Not every Swiss SRO affiliation covers every financial activity.
For example, where a particular SRO does not cover financial-advisory activity, an additional registration with an appropriate Swiss supervisory organisation may be required.
This can often be added separately without changing the underlying company structure.
Prices have moved
Demand for good Swiss escrow structures has increased substantially.
As a result, buyers should no longer expect to acquire a credible, operationally useful Swiss escrow structure at the prices seen in previous years.
Today, realistic acquisition prices generally are considerably higher, depending on the company’s history, existing banking relationships, regulatory status and infrastructure.
For current prices, contact us at insight@fintechlex.com
The important point is therefore not simply to find the cheapest company.
It is to acquire a structure that can actually obtain — and retain — the bank accounts, safeguarding arrangements and payment infrastructure required for the intended business model.
The real value is the complete infrastructure
Buying the company is only the beginning.
FintechLex can assist with the complete structure:
Swiss company + SRO framework + escrow banking + operating accounts + crypto banking where appropriate + EMI/payment partnerships + cards + white-label infrastructure.
That combination can support anything from a traditional escrow business to a specialised crypto service, payment company or fully branded neobank.
Because individual opportunities are often sold quickly, we maintain a rotating selection rather than advertising one specific company.
Current availability and pricing are provided to qualified buyers on request.
📩 FintechLex — insight@fintechlex.com