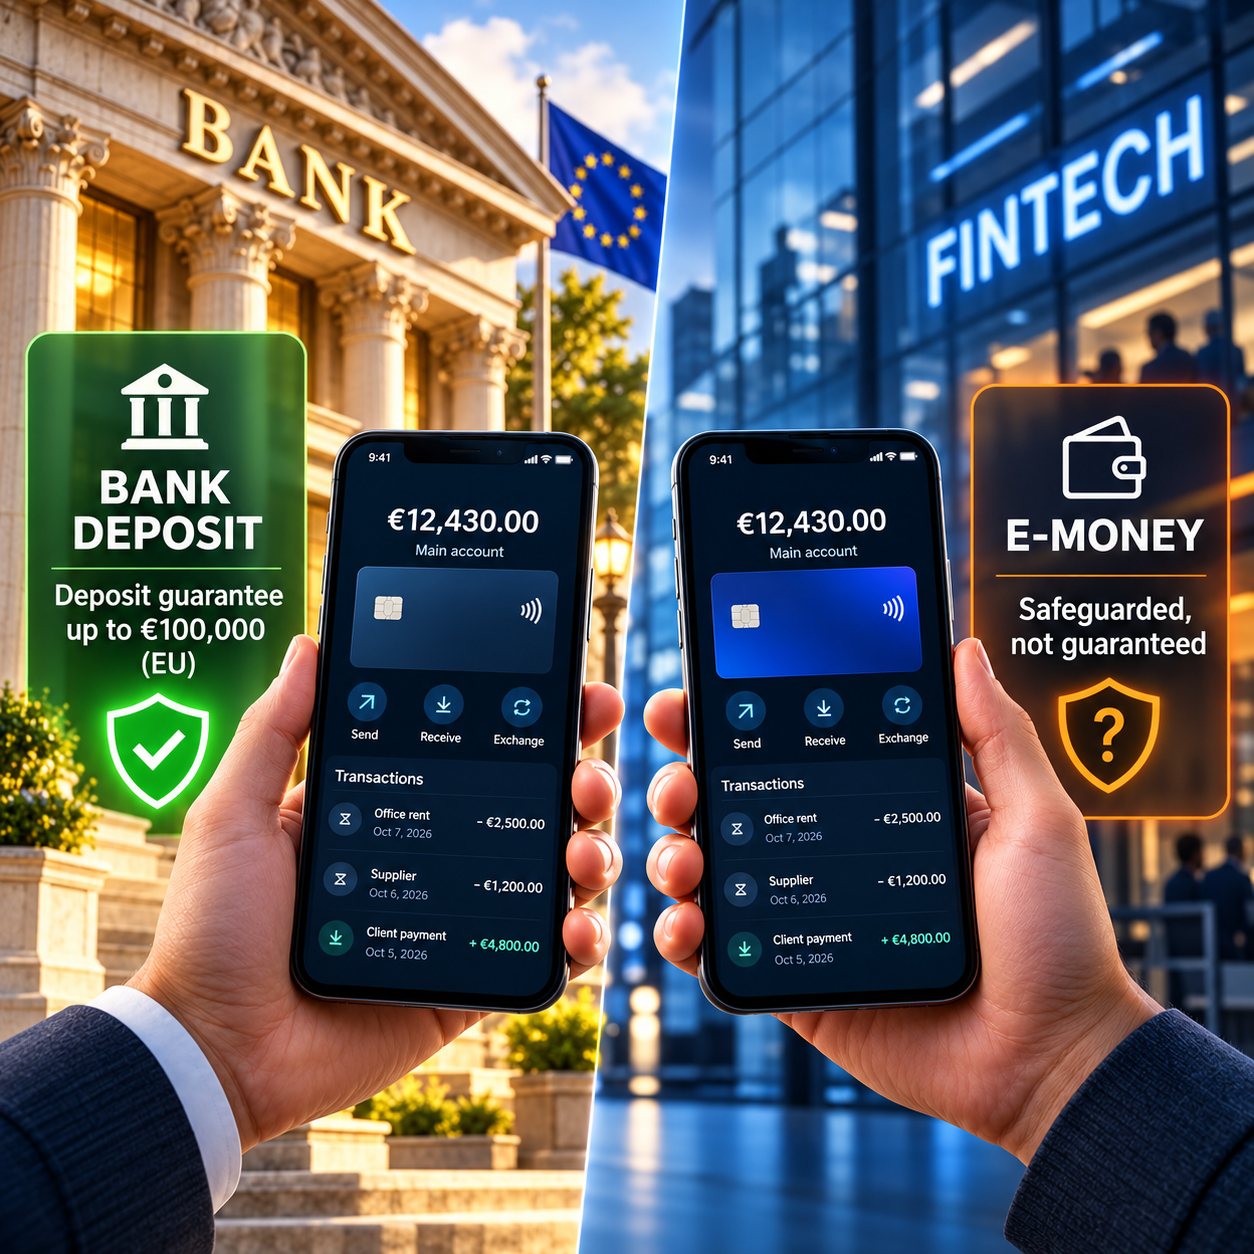
Two people open the same app, see the same logo, the same balance, the same card. One has a bank deposit. The other holds e-money. As long as everything works, there is no difference. If the company behind the app fails, there is a big one.
This guide explains the three ways a fintech can hold your money, what protects each one, and the questions to ask before you trust a provider with your company’s cash.
1. A bank deposit
If the company behind the app is a bank, your money is a deposit. The bank may lend it out and use it, which is precisely why banks are so heavily regulated. In return, deposits are covered by a deposit guarantee scheme: up to EUR 100,000 per depositor and per bank in the EU, and up to CHF 100,000 in Switzerland.
If the bank fails, the scheme pays out up to that limit, quickly and without you having to prove anything. Above the limit, you are an ordinary creditor.
2. E-money and payment accounts: safeguarded, not guaranteed
Most fintech apps are not banks. They are electronic money institutions (EMIs) or payment institutions. They may hold your money, but they may not lend it or use it. Instead, they must safeguard it, in one of three ways:
- kept in a separate account at a bank, apart from the company’s own money;
- invested in secure, low-risk and liquid assets;
- or covered by an insurance policy or a bank guarantee.
If the EMI fails, the safeguarded money is ring-fenced: it belongs to the clients, not to the company’s other creditors. That is real protection. But it is not a guarantee scheme. There is no fund that pays you within days. An administrator has to reconcile the accounts, establish who owns what, deduct its own costs, and only then return the money. That can take months.
And safeguarding only protects you if it was done properly. Where records are incomplete or the reconciliation does not match, the shortfall is shared among the clients.
There is a second, less known risk: the bank that holds the safeguarded account. If that bank fails, the deposit guarantee does not automatically protect the EMI’s clients. The account is in the EMI’s name, and deposits held by financial institutions are generally excluded from deposit guarantee schemes.
3. Neither: money held through a partner
A growing number of apps hold no licence at all. They run on a partner’s infrastructure, a white-label or banking-as-a-service model: the partner bank or EMI holds the money; the app holds the brand and the client relationship. That is legitimate, and often the smartest way to launch, as we explain in our white-label banking guide.
But your protection now depends on the partner, and on how the money is recorded between the app and the partner. In 2024 the collapse of Synapse, an American intermediary between fintech apps and banks, showed the risk: end customers could not reach their money for months because nobody could say precisely whose money was where.
When the chain breaks
Even without a failure, a problem at one link can freeze everything. In 2020, when Wirecard collapsed, the UK regulator froze its British card subsidiary, and customers of several well-known fintech apps lost access to their cards for days. Their app had done nothing wrong. Its partner had.
Regulators have drawn the lesson. Safeguarding is now one of the first things they inspect, and the UK tightened its rules for payment and e-money firms from May 2026, with more frequent reporting and independent audits.
And in Switzerland?
Switzerland has no EMI licence. Bank deposits are covered up to CHF 100,000. Money held by a fintech-licence holder is not covered by depositor protection and has no special status in bankruptcy, as we explain in Switzerland’s Fintech Licence Failed. The planned payment instrument institution will change this: client funds will have to be segregated and kept out of the bankruptcy estate.
Bank or EMI: side by side
| Bank (credit institution) | E-money institution (EMI) | |
|---|---|---|
| Legal protection | Deposit guarantee, up to EUR 100,000 per depositor and per bank (CHF 100,000 in Switzerland) | Safeguarding: client funds kept separate from the EMI’s own money |
| How it works | The bank may lend your money to other clients | The EMI may not lend your money; it keeps it in a segregated account at a partner bank, or in secure low-risk assets |
| If the institution fails | The guarantee scheme pays you, up to the limit, within days | Your funds are ring-fenced from other creditors, but an administrator must reconcile and return them: usually months, and costs may be deducted |
| Remaining risk | Amounts above the guarantee limit | Failure of the partner bank holding the safeguarded funds, or poor safeguarding and reconciliation by the EMI |
Five questions to ask your provider
- Which legal entity holds my money? Not the brand: the company named in the terms and conditions.
- Is it a bank, an EMI, a payment institution, or none of these?
- If it is not a bank, how is my money safeguarded, and with which bank?
- If it works through a partner, who is the partner, and is my money recorded in my name?
- What happens, concretely, if the company fails? A serious provider answers this in one paragraph.
For a company, the practical rule is simple: keep operating cash where it is useful, and keep reserves at a bank, spread across more than one institution.
If you are building the fintech
Safeguarding is not paperwork. It is the heart of your licence. Choose the safeguarding bank early, reconcile every day, and document who owns every franc and every euro. Regulators forgive many things in a young company; a gap in client money is not one of them. See our EMI licence guide and which licence your fintech actually needs.
Ask us to review your safeguarding set-up, or write to insight@fintechlex.com.
This article is for general information only and does not constitute legal advice.