 By Rene Philippe Raymond Dubout · · Updated
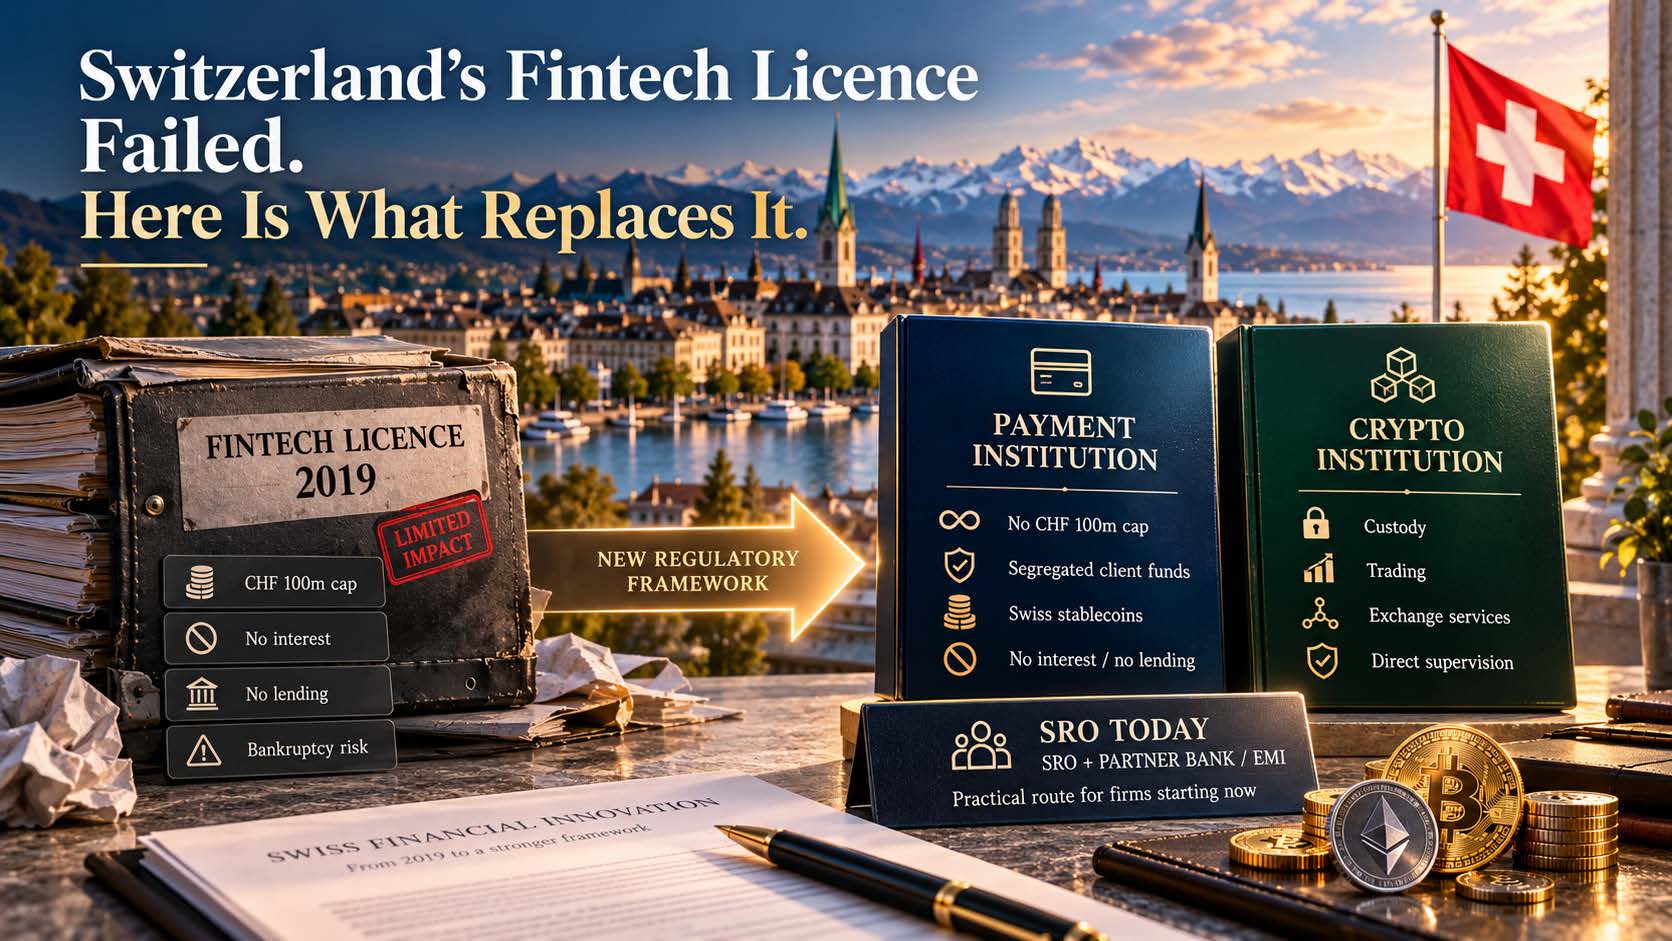
When Switzerland launched the fintech licence in 2019, the idea was elegant: a “banking licence light” for innovative firms that wanted to hold client money without carrying the full weight of a bank. Seven years later, FINMA’s register lists six holders, and two earlier holders ended in bankruptcy. Bern has drawn its own conclusion and has proposed a replacement.
Founders still ask me the same question every week: should I use an SRO company, the Swiss fintech licence, or an EMI in the European Union? The honest answer is that the three were never interchangeable. They do different jobs. Here is the comparison first, then the story of why the middle option failed and what Switzerland wants to put in its place.
SRO, fintech licence or EU EMI: the short answer
Put the three side by side and the choice becomes much easier, once you know what happens to your client’s money.
| Swiss SRO affiliation | Swiss fintech licence (today) | EU e-money institution (EMI) | |
|---|---|---|---|
| What it lets you do | Financial intermediation under anti-money laundering supervision: certain payment, exchange, crypto and credit activities, where no other licence is needed | Accept public deposits up to CHF 100 million (some money does not count, see below), without paying interest on them and without investing or lending them | Issue e-money and provide payment services; no interest for holding e-money and no lending of client funds (limited payment-related credit is allowed) |
| Client money | Affiliation does not allow you to take public deposits: client money sits with a bank or a licensed partner, or under a legal exception such as a settlement account | Held by you, but not privileged and not covered by deposit insurance: in a bankruptcy, clients are ordinary creditors | Safeguarded: kept apart from the EMI’s own money, or covered by insurance or a bank guarantee |
| Supervisor | A self-regulatory organisation recognised by FINMA, for anti-money laundering only: it is not a prudential licence | FINMA directly | The national regulator, for example the Bank of Lithuania or the Central Bank of Ireland |
| Capital | No regulatory minimum from affiliation; company law applies | 3% of public deposits and qualifying crypto held for clients, at least CHF 300,000 | Initial capital of at least EUR 350,000, plus ongoing own funds |
| Time to get there | Much shorter if you buy an existing SRO company; the new owners still go through the SRO and the bank | Several months, often a year, from scratch | Several months, often a year or more; buying one also needs the regulator’s approval |
| Passport to Europe | No | No | Yes, across the European Economic Area, after notification |
| What the reform changes | Some payment and crypto activities would move under direct FINMA supervision | Replaced by the payment instrument institution, with continuity for existing holders | Nothing: EU rules apply |
One common mistake while we are at it: SRO affiliation is anti-money laundering supervision, not a licence to do anything you like. Professional portfolio management, for example, needs its own FINMA licence. Buying an SRO company for the wrong activity is like buying a taxi licence to run a bus company.
In other words: if your business fits the SRO framework and you need to move quickly, an existing SRO company is the fast door. If you want to issue e-money and sell payment services to Europeans, you need an EMI, built or bought; if you only need payment services, a payment institution may be enough. Neither Swiss route gives you a passport to Europe. The Swiss fintech licence sat in between: too heavy to be quick, too limited to be profitable, and with no passport. That is exactly where it died.
A licence nobody wanted
In its December 2022 evaluation, the Federal Council admitted that the fintech licence had achieved only limited market success. That is official language for a flop. Its own count: between 2019 and mid-2022, four institutions obtained the licence, and FINMA opened bankruptcy proceedings against one of them.
The design explains why. A fintech licence holder may accept public deposits up to CHF 100 million, but may not pay interest on them and may not invest or lend them. The business earns fees, not margin. In practice, it is a bank with the profit engine removed.
What counts towards the CHF 100 million, and what does not
Only public deposits count. Money from banks and other supervised firms, from institutional investors with a professional treasury, from your qualifying shareholders and your own staff, and settlement balances cleared within 60 days do not. The test for a corporate client is a real treasury function, not a label: “professional” on the account opening form is not enough. FINMA can also allow more than CHF 100 million in special cases, if the money is neither invested nor paid interest and clients are specially protected; nobody has tested that door yet. Crypto held collectively for clients is a separate question: the Federal Council’s view is that the cap does not apply to it; not everyone agrees. And crossing the CHF 100 million line does not turn the licence into a bank.
Clients had little reason to prefer it either. If a fintech institution goes bankrupt, client cash is neither privileged nor covered by deposit insurance. It is an ordinary claim in the bankruptcy. Add the fact that a Swiss licence gives no access to the EU market, and most founders made the rational choice. They ran their payment business through an SRO company, with a licensed partner holding client money, or they went to Lithuania or Ireland. How that SRO route works for crypto businesses is explained in our Swiss Crypto Licence 2026 guide.
The “path to a bank” that nobody took
Back in 2024, the fintech licence was still sold, including on our own old blog, as the smart first step to a full banking licence: start small, grow your deposits, and upgrade when you pass CHF 100 million, while an EU EMI would have to start a bank application from zero. That comparison was too neat. There is no upgrade button. A bank application has to meet the full banking requirements, whatever licence you held before. A fintech licence gives you experience, systems and a track record, exactly like an EMI does. Neither is a shortcut.
And to build a large deposit base without paying a cent of interest, you need clients who love you for something else entirely. Very few fintechs had them. When a regulator builds a ladder and almost nobody climbs it, the problem is usually the ladder.
When the weakness became real
In 2022, FINMA opened bankruptcy proceedings against a fintech licence holder for the first time: Mogli AG. It was an early warning that a lighter licence does not make a fragile business model work.
On 4 March 2025 it happened again, this time in Geneva. FINMA opened bankruptcy proceedings against Swiss4.0 over justified concerns that the firm was over-indebted and had serious liquidity problems. It was a micro start-up with around 250 clients. Those 250 clients became ordinary creditors.
FINMA’s own comment was remarkably candid. Low entry requirements, it said, also mean a higher probability that a business model turns out not to work. That is a fair point, but the clients are the ones who pay for it.
What comes next: two proposed licences
The Federal Council has proposed amendments to the Financial Institutions Act (FinIA). The consultation closed on 6 February 2026, and the published timetable was a proposal to Parliament in the second half of 2026 at the earliest. Parliament still has to debate it, then come the implementing rules. Count on 2027 or 2028 as a planning assumption, not a date anybody has promised. Until then, today’s rules apply.
1. The payment instrument institution
This is the proposed successor to the fintech licence, and it goes after its main flaws:
- The CHF 100 million cap would disappear.
- It also reaches into the SRO world: the draft captures businesses that professionally accept client funds, so some SRO companies holding client money could need this licence, depending on their model and the exceptions kept in the implementing rules.
- The money backing client funds would be kept separately and stay out of the bankruptcy estate. Swiss4.0’s clients would have been in a very different position.
- It would become the route for issuing Swiss stablecoins: tied to one official currency, fully backed, redeemable at par. The issuer would notify FINMA at least 60 days before the first issuance and publish a white paper no later than that issuance.
- What would not change: no interest on client funds and no lending of them. A payment instrument institution would still not be a bank.
- What would change the economics: the institution could keep the income from investing the reserves in short-dated, high-quality assets, as long as the coverage rules are met. For the first time, the model could earn something on the float. Run the numbers on that before you decide anything.
2. The crypto institution
This would be a new prudential licence for crypto service providers:
- It would cover custody (with staking under dedicated rules), dealing for clients in the provider’s own name, and some short-term proprietary dealing.
- It applies to “cryptoassets for trading”. Utility tokens, financial instruments, bank deposits and the new regulated Swiss stablecoins fall outside that category; foreign stablecoins may fall inside it.
- Activities that run today on SRO affiliation alone, above all custody and dealing for clients, would move under direct FINMA supervision. Pure investment for your own account and genuinely non-custodial wallets are not automatically caught.
- The rules would be modelled on the securities firm regime, adapted to crypto.
What this means for you today
The transition rules in the draft are better news than most people think. Firms that already hold a licence for an activity would not need a new one; they would get one year to meet the new requirements. Businesses newly caught by the law would get one year to apply, and could keep operating in the meantime as long as they are affiliated with an SRO and supervised by it. In other words, an SRO company bought today is not a dead end. It is the waiting room, and it is the only one with the lights on.
For crypto and payment businesses on SRO affiliation, the message is simple: check which parts of your model the proposal actually catches, and plan the structure now: capital, governance, segregation of client assets, the audit set-up. The firms that prepare will be ready when the new regime opens. The rest will still be reading the law.
The Swiss4.0 case is a useful reminder that a licence is not a business model. Regulators can lower the entry barrier. They cannot make your revenue appear.
The route we recommend
If you need to be operating in Switzerland soon and your activity fits the SRO framework, buy an existing SRO company rather than wait months for a new affiliation, and design it from day one for the payment or crypto institution it may have to become. If you need Europe, look at an EMI that is already licensed and passported, or a payment institution if payments are all you need, instead of starting an application that can eat a year.
Buying is faster, not magic. The new owners still have to be accepted by the SRO or the regulator, and you still need a bank that says yes. That is precisely the work we do. FintechLex has SRO companies and EMIs on its books, in Switzerland and in the European Union, and we handle the due diligence, the change-of-control approvals and the bank accounts.
Tell us what you want to run and where your clients are, and we will tell you which door is the right one, and what it really costs, before you spend a franc. Write to insight@fintechlex.com, or see the companies currently for sale in our Marketplace.
For a detailed look at both proposed licences, read our earlier article: Two New Swiss Fintech Licences: Get Ready First. If you are starting now, an SRO company remains the fastest way in: see our Swiss SRO Licence 2026 guide.
This article is for general information only and does not constitute legal advice.
Sources
- FINMA, register of fintech licence holders (Article 1b Banking Act), checked 23 October 2026.
- Federal Council, evaluation report on the fintech licence, 16 December 2022.
- Banking Act, Article 1b (public deposits up to CHF 100 million; FINMA exception in special cases, paragraph 5).
- Banking Ordinance, Articles 5, 5a and 17a, and FINMA Circular 2008/3 (what counts as a public deposit; minimum capital).
- Federal Council, dispatch on distributed ledger technology, 2019 (crypto held collectively for clients).
- FINMA, Swiss4.0 SA in liquidation, 4 March 2025.
- State Secretariat for International Finance, fact sheet on stablecoins and crypto institutions, 22 October 2025.
- Federal Council, consultation draft amending the Financial Institutions Act and explanatory report, 22 October 2025 (Articles 51i, 51k and 74b).
- EU E-Money Directive 2009/110/EC and Payment Services Directive (EU) 2015/2366 (capital, safeguarding, passporting).