For years, a Swiss crypto business had one main regulatory question: which SRO do I join? That is about to change.
The Federal Council’s draft reform of the Financial Institutions Act, published for consultation on 22 October 2025, creates two new FINMA licences: the payment instrument institution and the crypto institution. Many crypto activities that today only require SRO affiliation for anti-money laundering purposes would move under direct prudential supervision by FINMA.
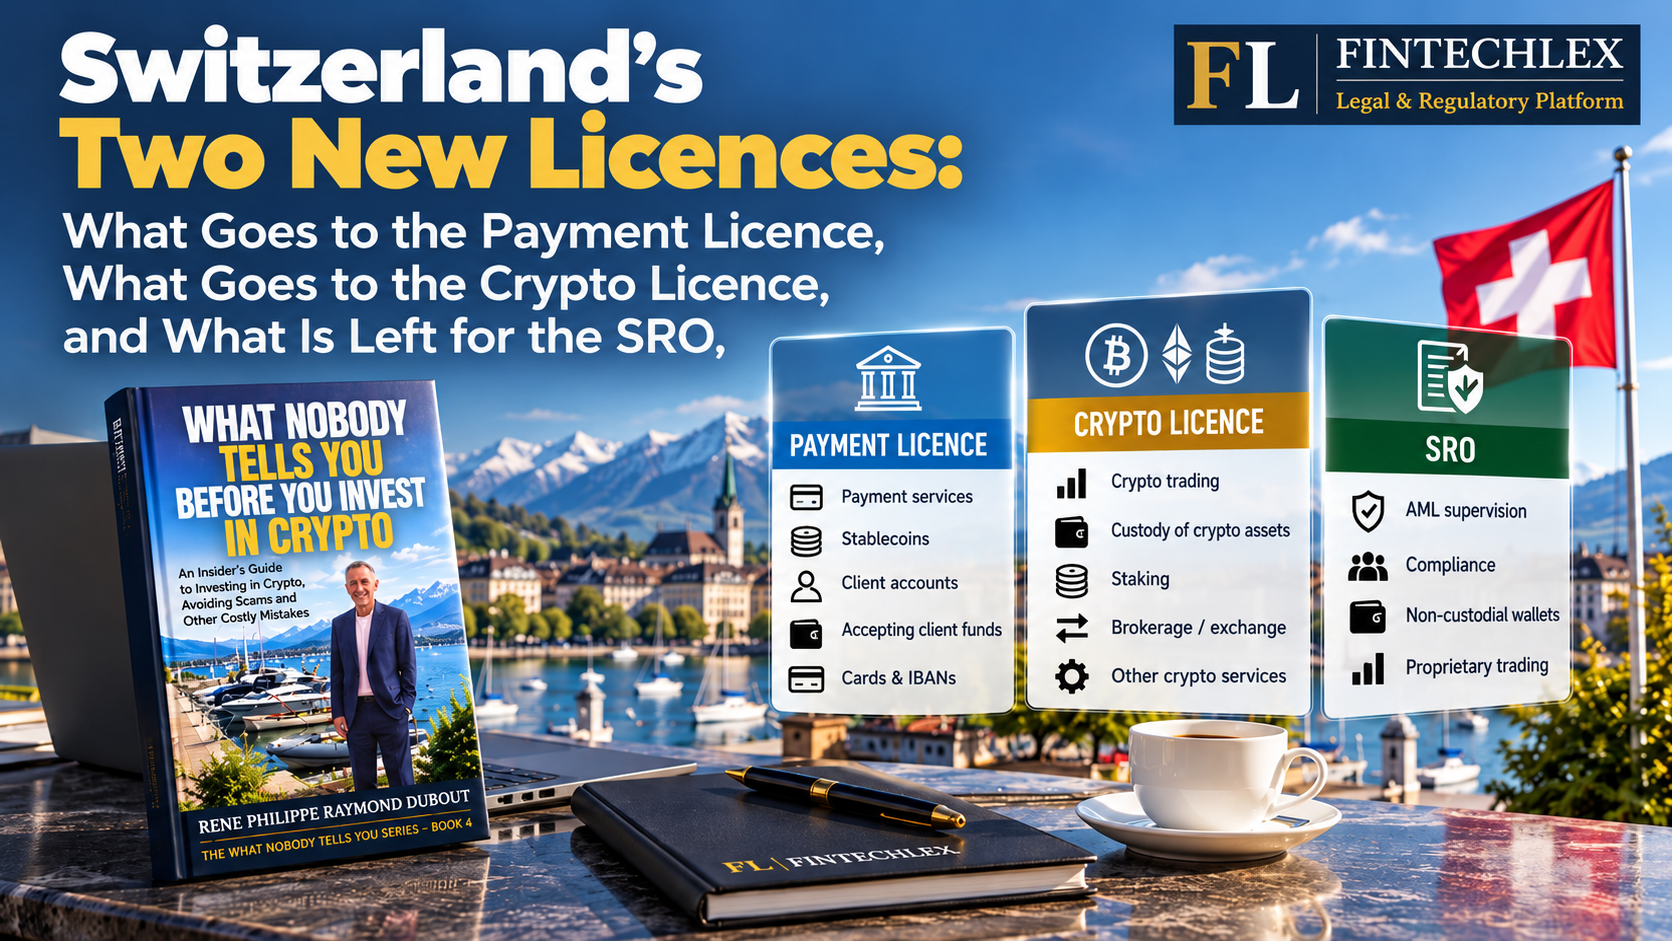
So three questions matter for every crypto business in Switzerland. What goes to the payment licence? What goes to the crypto licence? And what is left for the SRO?
Everything below describes the consultation draft. As of today, the bill is not yet before Parliament, and details may change.
1. The payment instrument institution: money and Swiss stablecoins
We covered this licence in Stablecoin Licence Switzerland. In short, it is the successor to the FinTech licence. It accepts client funds without paying interest or lending them, keeps them segregated from its own assets, provides payment services, and has the exclusive right to issue Swiss stablecoins: coins issued in Switzerland and backed by a single state currency.
It may also hold Swiss stablecoins in custody, under the same conditions as a crypto institution, without needing a second licence for that.
2. The crypto institution: custody, trading and market making
The crypto institution is a new licence, modelled on the securities firm. Under draft Article 51r, it is required for anyone who, on a commercial basis:
- holds crypto-assets in custody for clients, both Swiss stablecoins and other crypto-assets “with trading character”, such as Bitcoin, Ether or foreign stablecoins;
- trades crypto-assets in its own name for the account of clients; or
- acts as a market maker: trades short-term for its own account while quoting prices to the public.
Two points deserve attention.
First, custody is caught even when assets are held individually for each client. Today, individually allocated custody can often be run under an SRO. Under the draft, custody of client crypto-assets, individually or collectively, requires the licence. Client assets must be kept separate from the institution’s own assets, and custody may be delegated abroad only to an appropriately regulated sub-custodian.
Second, the licence also covers a trading platform, but only one that trades crypto-assets exclusively. A platform for tokenized shares or bonds is a different matter, because those are financial instruments.
What else the crypto institution may do:
- Staking, but only for a crypto institution that holds the assets in custody, with risk management, full information to clients and a separate written agreement, outside the general terms and conditions (draft Article 51z).
- Client accounts in fiat, but only to settle trades, not as ordinary accounts (draft Article 51u).
And what it may not do:
- Uncovered positions: the draft prohibits uncovered transactions (Article 51r(2)). Margin trading, short selling and proprietary derivatives remain the business of banks and securities firms.
- Payment services: they belong to the payment instrument institution.
- Issuing Swiss stablecoins: reserved to the payment instrument institution.
- Services on tokenized securities: those are financial instruments, outside this licence.
Minimum capital is required and must be fully paid in, but the amount is left to the ordinance. Own funds, liquidity and risk diversification rules apply, on an individual and, for groups, a consolidated basis.
3. One company, two licences?
This is where a lot of misinformation circulates.
Lenz & Staehelin read the explanatory report as granting the new licences only to separate legal entities. We did not find that statement in the draft Act or in the report. What the report does say is narrower: no other licence covers the activity of a payment instrument institution, not even a bank licence, so a bank must set up a separate company to issue Swiss stablecoins, to avoid mixing public deposits and client funds in the same legal entity.
In our view, this separation follows from how the Financial Institutions Act was built in 2015: each licence is defined by its activity, and only the cascade of Article 6 lets one licence cover another. The draft deliberately leaves the payment instrument institution out of that cascade, and the report ties the bank separation to exactly that choice. Whether one company could hold both new licences is not addressed expressly. Planning a structure around the new licences? Talk to us.
In practice, plan for two companies. That is also what I would advise anyway: keep client money and stablecoin issuance in one entity, and custody and trading of crypto-assets in another. We explain why in Stablecoins: When Even a Bank Needs a Separately Licensed Subsidiary.
Why two companies?
The logic is simple once you look at what each licence protects.
The Federal Council’s explanatory report is explicit: a bank that wants to issue a stablecoin will have to do so through a separate subsidiary licensed as a payment instrument institution. The Federal Council considers that setting up a subsidiary is “not an excessive hurdle” for a bank.
The Swiss Bankers Association disagrees and wants banks to issue directly under their banking licence. Parliament will have the last word.
Ground for the Separation.
- A long-standing Swiss principle. In Switzerland, a licence covers a defined scope of activities, set out in the company’s articles of association and organisational rules, and FINMA authorises only that scope. Some institutions are already confined by law to specific activities; fund management companies are the classic example. The reform applies the same logic: a payment instrument institution does payments and stablecoins, a crypto institution does crypto, and neither carries the other on its balance sheet.
- Two different kinds of risk. A payment instrument institution holds client money one for one, in sight deposits and short-term liquid assets, with no lending and no interest paid. A crypto institution carries market, custody and operational risk on volatile assets. Put both in the same company, and a trading or custody loss can eat into the money that backs client balances and stablecoins.
- Two different capital logics. The own funds of a payment instrument institution are built around safeguarding client money. Those of a crypto institution are built around market and custody risk. Separate companies keep each calculation clean and each failure contained.
- Cyber risk. A company that holds crypto-assets is a target for hackers. If an attack succeeds, it is far better that the loss sits in the crypto company than in the one holding client money.
Can the same person own both companies?
Yes. Nothing in Swiss law prevents one person or one holding company from owning two companies with two different FINMA licences. It is the classic holding structure. But FINMA will look closely at four points:
- Qualified shareholders. Anyone holding 10% or more of the capital or votes is a qualified shareholder of each company. FINMA checks their reputation and that their influence does not harm sound and prudent management. Having passed this test for one licence helps, but it is checked again for the second.
- Real separation. Separate capital, separate own funds, separate client money, separate balance sheets. The crypto company must not be able to draw on the payment company’s client funds or stablecoin reserves, directly or through intra-group arrangements.
- Governance and conflicts of interest. Each company needs its own governance, as FINMA requires for banks and securities firms: a board of directors separate from executive management, with independent members able to ensure that each company is run in its own interest, not to favour the other. Each company must have its own executive management, distinct from the other, and its own independent directors.
- Group supervision. Where a crypto institution dominates a financial group, the banking rules on financial groups apply by analogy (draft Article 51z bis). FINMA will then look at the group as a whole, including whether the same money is being used twice to capitalise both companies.
Note also the cascade: a bank licence, and the licence of a securities firm that holds client accounts, would also cover the crypto institution activities. The payment instrument institution is not part of that cascade.
4. What is left for the SRO?
More than many fear, but less than today. Based on the draft, these activities would not, by themselves, require the crypto institution licence:
- Pure proprietary trading, without quoting prices to the public.
- Brokerage of Swiss stablecoins: secondary trading in Swiss stablecoins is not regulated like other crypto-assets.
- Crypto portfolio management, which stays outside the licence but becomes subject to conduct rules.
- Non-custodial wallets, where the client alone controls the assets.
Where these activities qualify as financial intermediation, the anti-money laundering duties remain, and so does the SRO affiliation.
What leaves the SRO world is the core of most crypto business models: holding client assets, and trading for clients in your own name. A crypto broker or custodian that operates today under an SRO will have to apply to FINMA within one year of entry into force. It may continue in the meantime, but only if it stays affiliated with an SRO until FINMA decides.
5. What this means for the market
This is the biggest change for Swiss crypto businesses since the SRO system was created.
- For existing SRO crypto companies: check now which of your activities fall under the new licence. If you hold client assets or trade in your own name, budget for capital, governance and a FINMA application.
- For buyers: the value of an SRO-affiliated crypto company will depend on what it does. A company whose activities stay outside the licence keeps its value; one that needs the licence becomes a licensing project. See what to check before buying a Swiss regulated company and our Swiss SRO companies for sale.
- For everyone: the old question “which SRO?” becomes “which licence, and in which company?”
Running a crypto business under an SRO, or planning one? Write to insight@fintechlex.com.
Based on the Federal Council’s consultation draft of 22 October 2025 (Financial Institutions Act, Financial Services Act and Financial Market Infrastructure Act), the State Secretariat for International Finance factsheet and published analyses. The bill is not yet before Parliament and the ordinance is not yet published. General information, not legal advice.