
Switzerland is globally recognised for its financial services sector, supported by a comprehensive regulatory framework. This page is our map: what each Swiss licence allows, and where to read more. Each section links to our detailed guide.
The waterfall principle
A unique feature of the Swiss system under the Financial Institutions Act (FinIA) is the waterfall principle: a higher-tier licence includes the activities of all lower tiers. A bank licence covers what a securities firm may do; a securities firm licence covers portfolio management; and so on. One licence, chosen well, can cover your whole business.
1. SRO affiliation (anti-money laundering)
For financial intermediaries that do not need a FINMA licence: payment and exchange services, lending, trading in precious metals and commodities, and most crypto services: exchange, custody, brokerage and wallet services. The fastest and cheapest way to operate legally in Switzerland. Full guide: Swiss SRO Licence 2026: Requirements, Cost, Timeline.
2. Portfolio manager and trustee licences
Discretionary management of client portfolios, and professional trusteeship, both require a FINMA licence. Portfolio managers may also manage collective assets under the de minimis rule: up to CHF 100 million including leverage, or CHF 500 million unleveraged with no redemption rights for five years. Family offices: see When Does a Swiss Family Office Need a FINMA Licence?. Ready-made option: turnkey FINMA asset manager.
3. Fund management and L-QIF
Managers of collective assets above the de minimis thresholds need a fund management licence. Since 1 March 2024, the Limited Qualified Investor Fund (L-QIF) can be launched without FINMA authorisation, provided it is managed by a FINMA-supervised institution and reserved for qualified investors.
4. Securities firm
Formerly “securities dealer”. Trading for clients or for own account, market making, underwriting and custody. Minimum capital CHF 1.5 million. Full guide: Swiss Securities Brokerage Licence.
5. Fintech licence, and what replaces it
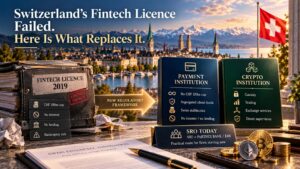
The “banking licence light” (art. 1b Banking Act) allows public deposits up to CHF 100 million, without interest or lending. It is being replaced by the payment instrument institution licence. See Switzerland’s Fintech Licence Failed.
6. Crypto businesses
Today mostly SRO; tomorrow the new crypto institution licence for custody and trading. See Swiss Crypto Licence 2026 and Token Classification.
7. Bank
The top of the waterfall: deposits, lending, everything else. Building one takes years; buying one is often faster. See Revolut in Switzerland: buy or build?.
Our Swiss team includes lawyers, bankers and bank auditors who provide business planning and licensing support. For current prices, contact us at insight@fintechlex.com.
This article is for general information only and does not constitute legal advice.