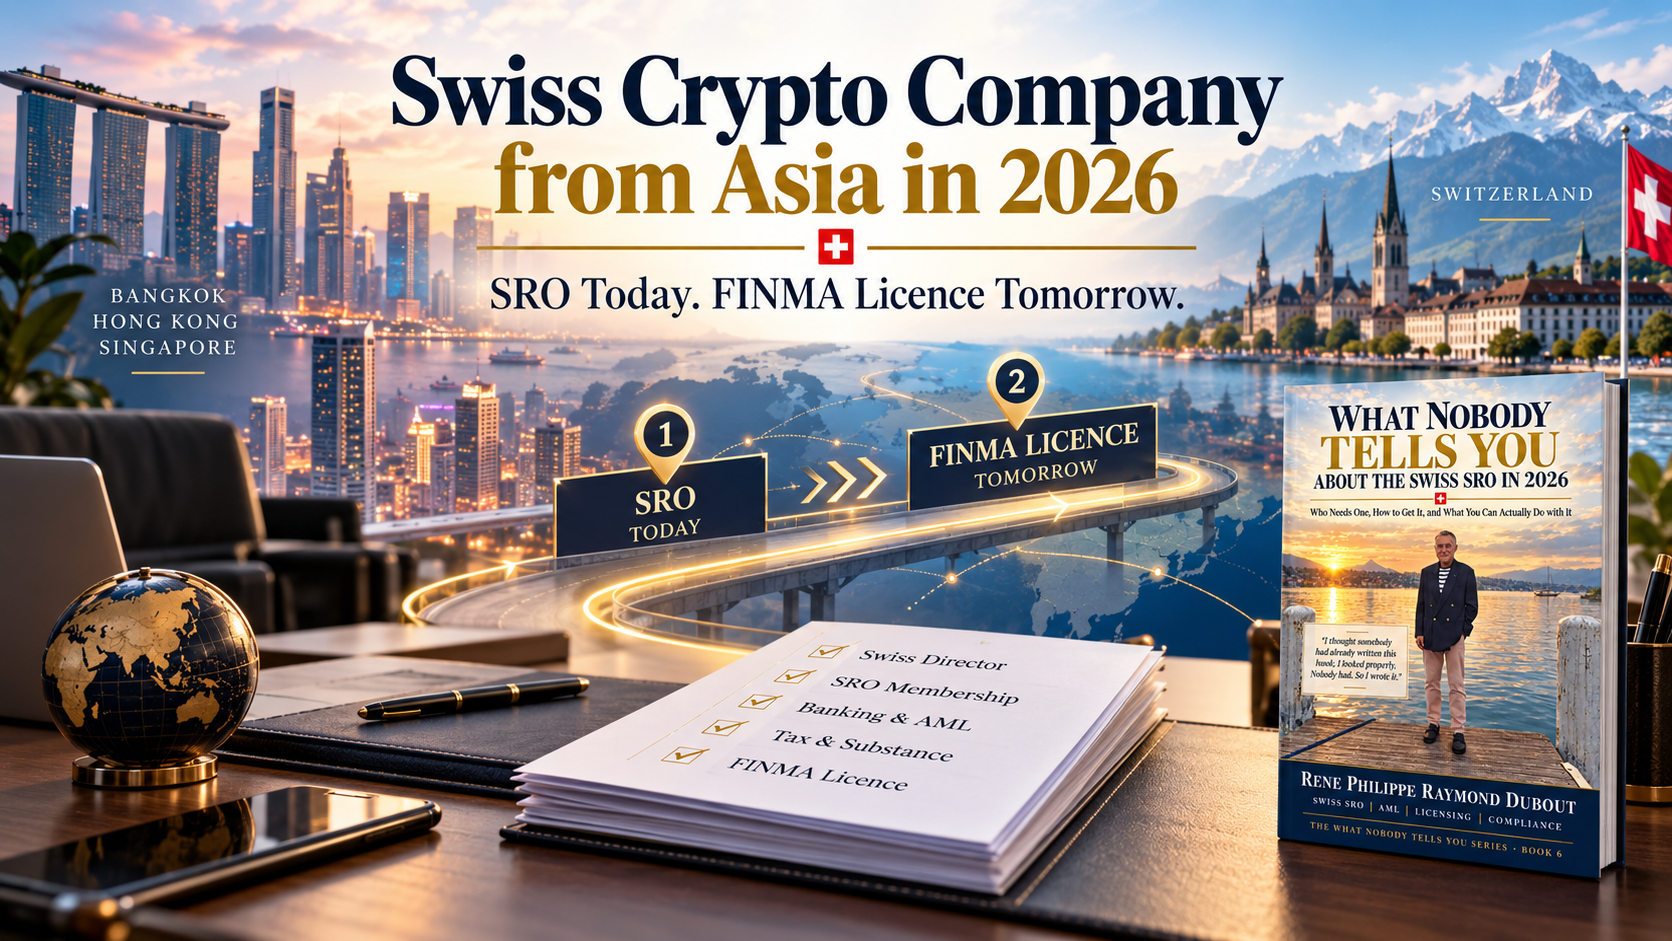
What a founder in Bangkok, Hong Kong or Singapore really has to plan: buy or build, the Swiss director, the bank, the cost, the tax trap, and the licence that is coming.
Every month, I get the same call. A founder in Bangkok, Hong Kong, Singapore or Ho Chi Minh City has a crypto business that works. Clients, volume, a product. What he does not have is a jurisdiction that European banks, institutional counterparties and serious investors take seriously. So he asks: “Can I just open a Swiss company and get an SRO?”
The short answer is yes. The long answer is this article. Switzerland is still one of the best places in the world to put a crypto business, but it is not a mailbox, and 2026 is a year of transition. What works today will not necessarily work in 2028. A founder who plans only for today will pay twice.
The short answer
- Yes, a founder living in Asia can own and run a Swiss crypto company. There is no Swiss nationality or residence requirement for shareholders. You do need at least one person authorised to sign for the company who lives in Switzerland.
- Most crypto activities start on an SRO, the self-regulatory organisation that supervises you for anti-money laundering. Exchange, brokerage, OTC, wallets, segregated custody and staking can run on it today.
- The bank account is the real bottleneck, not the SRO. For an Asian-owned company, the bank will look harder at the owners, the source of wealth and the countries of the clients.
- Three routes: build from scratch (about 4–5 months, from about CHF 89,000 plus share capital), buy a clean shell and apply (about 10–12 weeks, about CHF 129,000 all-in), or buy a company already admitted to an SRO (2–3 weeks, price on request).
- A new FINMA crypto-institution licence is coming for custody, trading for clients and market making. Plan the structure now so that you do not have to rebuild it in 2027 or 2028.
Why Switzerland, when you are based in Asia?
Founders sometimes ask me why they should bother. Singapore and Hong Kong are next door, Dubai is aggressive, and Europe has MiCA. Fair question. Here is what Switzerland gives an Asian crypto business that the others do not, or not in the same combination:
- Credibility with banks and counterparties. A Swiss company with a clean SRO record opens doors with liquidity providers, institutional clients and private banks that an offshore entity will never open.
- A proportionate entry point. You can start operating on SRO affiliation, at a fraction of the cost and time of a full licence. Singapore and Hong Kong expect you to hold their full licence before you serve clients, and the bar there is high.
- Legal certainty for crypto assets. Since the DLT Act, crypto assets held for clients can be separated from the custodian’s estate in bankruptcy, provided they are held for the client and allocated to him at all times.
- Access to private banking. For high-net-worth clients moving large crypto amounts into fiat, Geneva and Zurich have banks that know how to do it. Few places in Asia do.
What Switzerland does not give you is a passport into the EU. Switzerland is not in the European Union, so a Swiss crypto company has no MiCA passport. If your plan is retail clients across Europe, you will need a MiCA licence or an EU partner. For international, high-net-worth and B2B clients, Switzerland remains very hard to beat.
What the SRO lets you do today, and where it stops
A company that accepts, holds or transfers crypto assets for clients on a professional basis is a financial intermediary under the Anti-Money Laundering Act. It must join an SRO recognised by FINMA. On that basis, the following can run today without a FINMA licence:
| Activity | On an SRO today? | Condition |
|---|---|---|
| Crypto exchange (buy, sell, swap) | Yes | No client fiat held as deposits |
| Brokerage and OTC desk | Yes | Full KYC and transaction monitoring |
| Custodial wallets and cold custody | Yes | Assets segregated and allocated per client |
| Non-custodial wallets | Yes | Often outside the AML perimeter, depending on the model |
| Staking | Yes | Client assets segregated, terms disclosed |
| Crypto-backed loans | Yes | Lent from your own funds, never client money |
| Holding client fiat in accounts | No | Through a partner bank or EMI on a white-label basis |
| Issuing a stablecoin | No | Banking or fintech licence today; payment instrument institution after the reform |
The principle behind every line: the SRO supervises your anti-money laundering compliance. It does not authorise you to take deposits or to run an investment product. For the full map, see our Swiss Crypto Licence 2026 guide.
Buy or build: the first real decision
For a founder abroad, this decision matters more than for a Swiss founder, because every month without a working structure costs you clients you already have.
| Build from scratch | Shell company + application | Ready-made SRO company | |
|---|---|---|---|
| Time to operate | About 4–5 months | About 10–12 weeks | About 2–3 weeks |
| Indicative cost (CHF) | About 89,000 in fees, plus share capital | About 129,000 all-in | On request |
| Main risk | Refusal or slow review | Refusal or slow review | Hidden problems in the company’s past |
| Best for | Full control over name and design | Cost first, a 3-month runway is fine | Clients already waiting |
Buying a company already admitted to an SRO is not a way around compliance. The new owners and directors are checked by the SRO like any applicant, and any material change of activity must be reviewed. What you buy is time and, above all, the existing banking relationships. A cheap company with a damaged record or no bank is not a bargain. It is a liability.
The Swiss resident director: not a name on a form
Swiss law requires that at least one person authorised to represent the company lives in Switzerland (Code of Obligations, art. 718 para. 4 for a company limited by shares, art. 814 para. 3 for a limited liability company). This is why a Swiss resident director appears in every budget.
Founders from Asia often treat this person as a formality. That is a mistake, for three reasons:
- He carries personal liability. A serious Swiss director will want to understand the business, see the flow of funds and be informed before anything material changes. If he is not, he resigns, and you lose your signatory overnight.
- The SRO looks at him. Directors and managers must be fit and proper, with relevant experience. A “nominee” with no knowledge of crypto or anti-money laundering weakens your file.
- The bank looks at him. In many cases, the bank’s first meeting is with the Swiss director, not with you.
Budget around CHF 12,500 a year for a professional resident director on a lean set-up, more if the business is complex or high-volume.
The AML officer: where Asian set-ups usually fail
Your compliance officer must have genuine knowledge of Swiss anti-money laundering rules. It is tempting to give the job to your compliance team in Asia, who know your clients. The SRO will not accept a manual copied from Singapore or Hong Kong, and it will not accept an officer who cannot explain Swiss rules on risk classification, beneficial ownership and reporting to MROS, the Swiss Money Laundering Reporting Office.
What works in practice: a Swiss-qualified compliance officer, part-time at the start, who owns the Swiss directives and signs off on high-risk clients, with your Asian team doing the day-to-day onboarding under those directives. The SRO wants to see that decisions are made by people who understand the Swiss framework, not that every task is performed in Switzerland.
The bank account: plan it before you incorporate
This is the step that kills more Asian crypto projects in Switzerland than any regulator. The SRO admits you. The bank decides whether you can operate. For an Asian-owned crypto company, expect the bank to ask:
- Who the beneficial owners are, and how they made their money, with documents going back years. “Successful business in Thailand” is not an answer; audited accounts, tax returns and sale agreements are.
- Which countries your clients come from. Some Asian jurisdictions are on enhanced due diligence lists at many banks. Be ready to exclude some markets.
- How fiat flows. Which partner holds client money, and how it reaches the exchange.
- Why Switzerland. A bank wants to see a real reason for the Swiss company, not a flag of convenience.
The structures that work separate the layers: a crypto-friendly Swiss bank for corporate and treasury money; a private bank for high-net-worth and OTC clients moving large amounts; and a licensed electronic-money institution on a white-label basis for retail accounts, IBANs and cards. This is also why companies that already have working Swiss bank relationships sell at a premium.
The tax trap: managed from Bangkok, taxed in Bangkok?
This is the point I see ignored most often. A Swiss company is taxed in Switzerland. But if the real decisions are taken by the founder sitting in Bangkok, Hong Kong or Singapore, and the team that runs the business sits there too, the tax authority of that country may argue that the company has a permanent establishment there, or that it is effectively managed from there. Then you pay tax twice, or you pay it in the wrong place.
There is no single answer, because it depends on the country, the treaty and the facts. But three rules keep you out of trouble:
- Real decisions in Switzerland. Board meetings held in Switzerland, minuted, with the Swiss director actually deciding.
- A clear service contract with the Asian team. If your developers and support staff are in Asia, put them in a local service company that invoices the Swiss company at arm’s length. The Asian company is then taxed on its margin, and the Swiss company keeps its business.
- Choose the canton with the bank in mind. Zug has a lower profit tax than Geneva, but for an SRO business the private-banking relationships of Geneva often matter more than three points of tax.
On VAT, most SRO revenue, including payments, money exchange, lending and custody, is exempt without credit: you charge no VAT, but you cannot recover the VAT on your costs. Plan it from day one.
Serving clients in Asia
Swiss law does not stop a Swiss SRO company from onboarding clients from Asia. Swiss supervision looks at how you identify your clients and where their money comes from, not at their passport. An investor in Bangkok, Singapore or Hong Kong can open an account with a Swiss SRO company like anyone else, provided the KYC file holds.
The question sits on the other side: the rules of the client’s own country. Some Asian markets restrict who may offer digital-asset services to their residents, and the answer can depend on how the client found you, what you offer him and whether you market actively in his country. So check it country by country, when the time comes, before you start onboarding clients from a given market. It is a short review, and it is much cheaper done before than after.
What changes with the reform, and why it matters to you now
On 22 October 2025, the Federal Council opened a consultation, closed on 6 February 2026, on two new licences under the Financial Institutions Act:
- The crypto institution, for anyone who, on a commercial basis, holds crypto assets in custody for clients, trades crypto assets in its own name for the account of clients, or acts as a market maker. Under the draft, custody is caught even when assets are held individually for each client.
- The payment instrument institution, the successor to the fintech licence, which accepts client funds without paying interest or lending them, and which alone may issue Swiss stablecoins.
Under the draft, a crypto broker or custodian that operates today under an SRO will have to apply to FINMA within one year of entry into force. It may continue in the meantime, but only if it stays affiliated with an SRO until FINMA decides. Some activities are expected to stay on the SRO: pure proprietary trading without quoting prices to the public, non-custodial wallets, brokerage of Swiss stablecoins and crypto-only portfolio management, which becomes subject to conduct rules.
No date of entry into force has been set, and the bill is not yet before Parliament. But three consequences are already clear for a founder planning a structure now:
- Capital and governance will go up. A crypto institution will need minimum capital, own funds, liquidity rules, and a board separate from executive management. Budget for it rather than discover it.
- Plan two companies, not one. The reform keeps client money and stablecoin issuance in a payment instrument institution, and custody and trading in a crypto institution. My advice is to separate them anyway: one company that holds client money, another that holds crypto. If the crypto company is hacked, the loss stays there.
- Being in the system matters. Under the draft, the transition protects companies that are already operating under an SRO. A company that starts in 2026, builds a clean track record and bank relationships, and prepares its FINMA file in parallel will be in a far better position than one that arrives after the law is in force.
For the detail, read Switzerland’s Two New Licences: What Goes to the Payment Licence, What Goes to the Crypto Licence, and What Is Left for the SRO.
A realistic structure for an Asian founder
Every case is different, but this is the architecture we recommend most often in 2026:
| Layer | Where | Role |
|---|---|---|
| Holding company | Where the founder’s other assets sit (often Hong Kong or Singapore) | Owns the operating companies; keeps the founder’s position clean and transferable |
| Swiss crypto company | Geneva or Zug | Exchange, OTC, custody on an SRO today; FINMA crypto-institution file prepared in parallel |
| Fiat layer | Licensed bank or EMI partner | Client accounts, IBANs, cards on a white-label basis, until you hold your own licence |
| Asian service company | Where the team is | Technology, client support and onboarding under the Swiss directives, invoicing the Swiss company at arm’s length |
| Later: payment company | Switzerland, separate entity | If you want to hold client money or issue a Swiss stablecoin under the new payment licence |
Cost: what to put in the budget
| Item | Indicative cost |
|---|---|
| Set-up (route A, from scratch) | About CHF 89,000 in fees, plus share capital |
| Set-up (route B, shell + application) | About CHF 129,000 all-in |
| Share capital | AG: CHF 100,000 (at least 50,000 paid in); GmbH: CHF 20,000. Not a cost: it stays in the company |
| Running costs, lean set-up | From about CHF 30,000 a year (director, office, compliance, audit, SRO fees) |
| Crypto-specific layers | Exchange or custody software, liquidity providers, wallet infrastructure, white-label IBANs and cards |
| Future FINMA licence | Capital, own funds and governance to be set by the ordinance: budget for it from 2027 |
These are lean figures for a low-volume start. With real client flows, compliance and accounting grow with the number of clients and transactions.
Five mistakes Asian founders make in Switzerland
- Treating the resident director as a nominee. He signs, he is liable, and he can resign.
- Copying the compliance manual from Singapore. The SRO wants Swiss directives adapted to your actual business.
- Opening the company before talking to a bank. You end up with an SRO membership and nowhere to put the money.
- Running everything from Asia. It weakens the file with the SRO and creates a tax problem at home.
- Building for 2026 only. The crypto-institution licence is coming. A structure that cannot be split or capitalised later will cost you twice.
Frequently asked questions
Can a foreigner living in Asia own a Swiss crypto company?
Yes. Foreign ownership is common. The owners must be transparent and fit and proper, and the company needs at least one authorised signatory who lives in Switzerland.
Do I need to move to Switzerland?
No. You can own and direct the business from abroad, as long as the Swiss company has a resident signatory and real decision-making in Switzerland.
Can my investment in an SRO company get me a residence permit in Switzerland?
It can, but not a small one. A non-EU national who wants to live in Switzerland and run his own company has no right to a permit: the canton must be satisfied that the business is in Switzerland’s economic interest. In our experience, below CHF 1 million invested in the Swiss business, with real jobs created in Switzerland, the canton will not even consider the file. That threshold is not written in the law, but it is how the authorities work in practice. Buying an SRO company with two employees will not do it. Building a real operation in Switzerland around it can.
Will my SRO company still be valid after the reform?
For some activities, yes. Under the draft, custody, trading for clients and market making move to the new crypto-institution licence. A company already operating under an SRO would have one year from entry into force to apply, and could continue in the meantime.
How long does it take?
About 4–5 months from scratch, 10–12 weeks with a shell company, 2–3 weeks for a ready-made company already admitted to an SRO. The bank account can take longer than all of these.
Planning a Swiss crypto company from Asia?
Tell us what you want to offer, to whom and from where. We will tell you whether to buy or build, which SRO fits your model, where the banking and tax risks sit, and how to prepare for the crypto-institution licence. FintechLex works from Geneva, Hong Kong and London, and has worked in Asia since 1995. Write to insight@fintechlex.com or message us on WhatsApp.
See also the Swiss SRO companies currently for sale, and why buy a Swiss SRO company with us: every company is checked beforehand, with a due diligence report and a signed warranty.
Rene-Philippe — FintechLex SA, Geneva | Hong Kong | London
General information, not legal or tax advice. The crypto-institution and payment-instrument-institution licences are at the consultation-draft stage; the position described is that of October 2026. Costs are indicative FintechLex figures, October 2026.