Acquire the bank. Shape the launch.
Most banks for sale come with a past. This one comes with a future, and nothing else.
We are offering for sale a privately owned international bank in the Commonwealth of Dominica. It holds an offshore banking licence and a separate virtual asset registration, USD 1 million of regulatory capital sits in a segregated account, and a team of eight is already in place on the island. What it does not have is clients: banking operations have not started. For a buyer, that is precisely the point. No legacy book to clean up, no inherited customer you would never have accepted yourself, no history to explain to a correspondent bank. You set the commercial direction from day one, within the regulator’s framework.
What you are buying
- Two authorisations. An offshore banking licence, plus a separate virtual asset registration covering fiat-to-crypto exchange, transfers, safekeeping and administration, certain token issuer activities and related financial services.
- USD 1 million of regulatory capital, held in a segregated account and released only with the regulator’s written approval.
- A real local presence. An office in Dominica, a resident authorised agent and eight employees covering management, compliance and anti-money laundering, operations, technology support, business development and administration.
- A defined corporate market. International trading companies, IT firms, professional services, logistics operators, manufacturers and holding companies.
The engine is already being built
Getting a banking licence is the easy part. The money usually disappears afterwards, building the plumbing. Here, most of that work is well under way. The core banking system is selected, with back-office and web banking development and the main testing completed. Accounting runs. The identity-check and crypto compliance tools are implemented and being extended to the Travel Rule, wallet risk scoring and crypto monitoring. A digital-asset custody relationship is in place. Operational banking and payment accounts are open, API integrations are in progress, and further payment and digital-asset providers are being onboarded. A brokerage account opens the door to investment services.
Once onboarding, integrations and approvals are complete, the provider network is designed to support SWIFT, SEPA and SEPA Instant, Faster Payments, CHAPS, ACH and Fedwire, together with multi-currency accounts, FX and selected custody, exchange, transfer and stablecoin services. Web and mobile banking are part of the plan, and native iOS and Android apps are in development. The provider names and the status of each integration are shared with qualified buyers under NDA.
A clean model, on purpose
The bank is built for corporate clients: multi-currency accounts, international and local payments, FX, investment and brokerage access, and selected digital-asset services, with web and mobile banking. No retail banking. No accounts for other financial institutions, payment companies, electronic money institutions, money service businesses or crypto service providers, and no nested payment flows. Some buyers will call that a limit. Anyone who has ever tried to keep a correspondent bank will recognise it for what it is: the reason correspondent banks say yes.
What you should know before you call
Both the banking licence and the virtual asset registration run until 31 December 2026 and must then be renewed. The change of ownership also needs the regulator’s approval, as with any bank acquisition worth the name. We walk serious buyers through both before they commit a cent.
On request, we can also assist with opening two correspondent accounts, one in Switzerland and one in the EU, and with obtaining an active SWIFT code. In other words, the two steps that turn a licence into a bank people can actually pay.
Who it is for
Fintech founders who want their own regulated balance sheet instead of renting someone else’s. Crypto businesses that need fiat and digital assets under one roof. Trading groups and family offices with cross-border flows that are tired of having their accounts reviewed, frozen or closed by somebody else’s compliance department. If that sounds like you, this is a rare chance: a bank with its licences, its capital, its team and most of its technology in place, and a blank page where the clients will go.
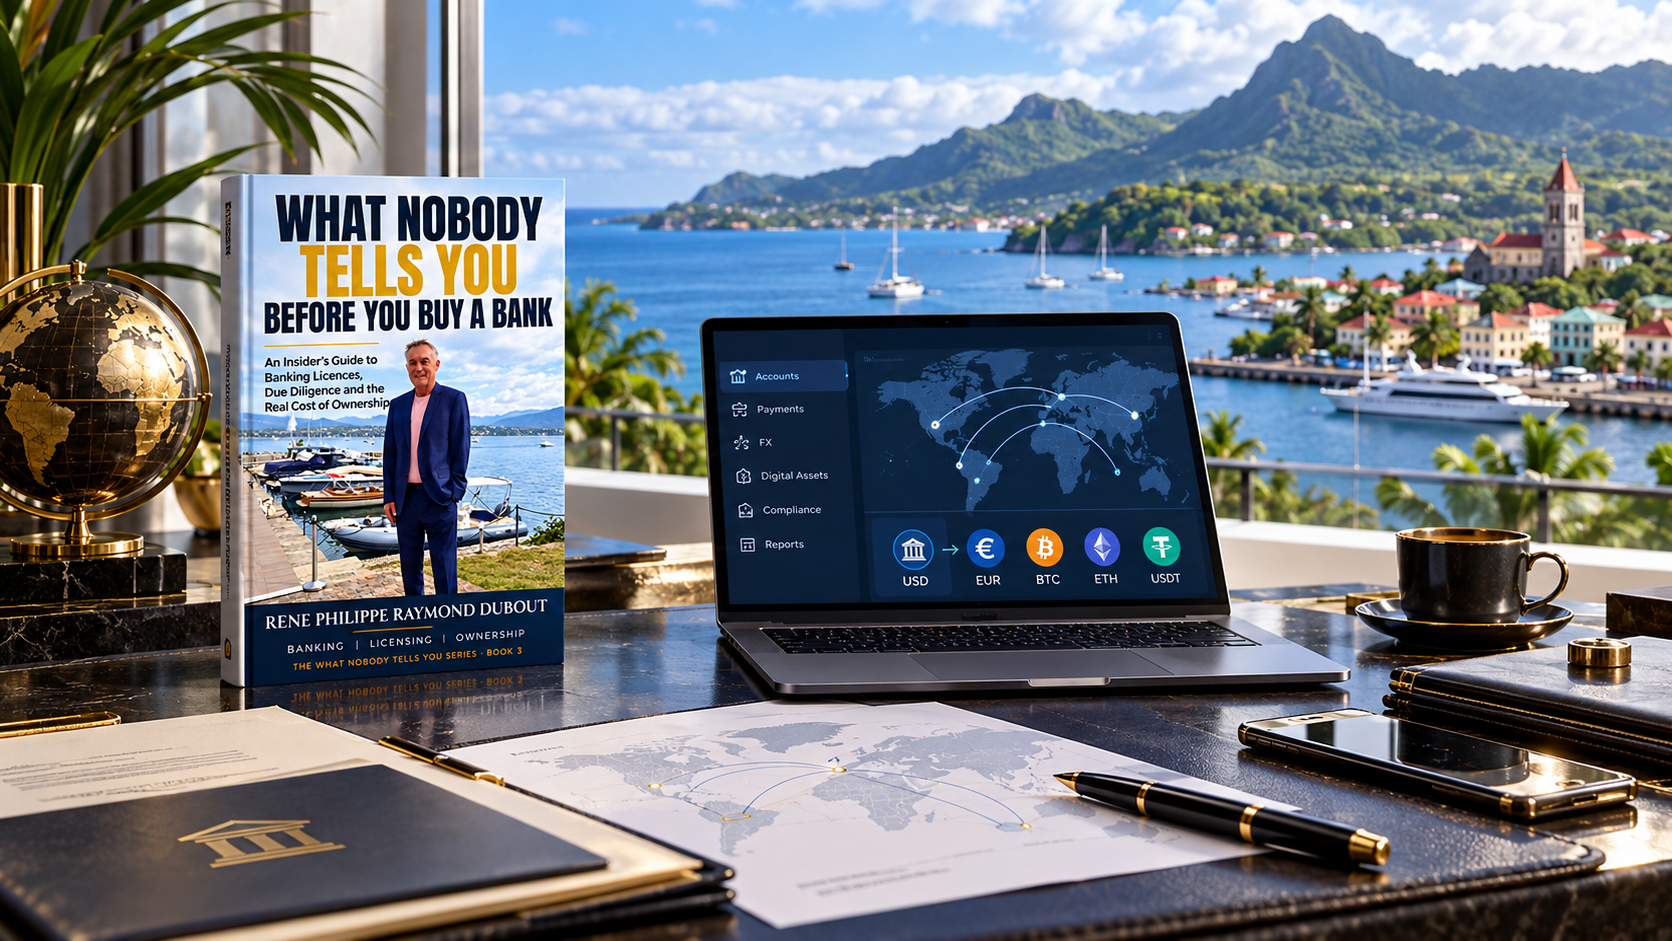
If you are new to buying a bank, read What Nobody Tells You Before You Buy a Bank first. It will save you a few expensive questions. Our articles on buying a banking licence or applying from scratch and how to build an offshore bank in 2026 explain the rest.
Price and next steps
Price on request. Further information, the full provider map and transaction discussions are available to qualified buyers under NDA.
Contact: insight@fintechlex.com or WhatsApp +41 787 983 770