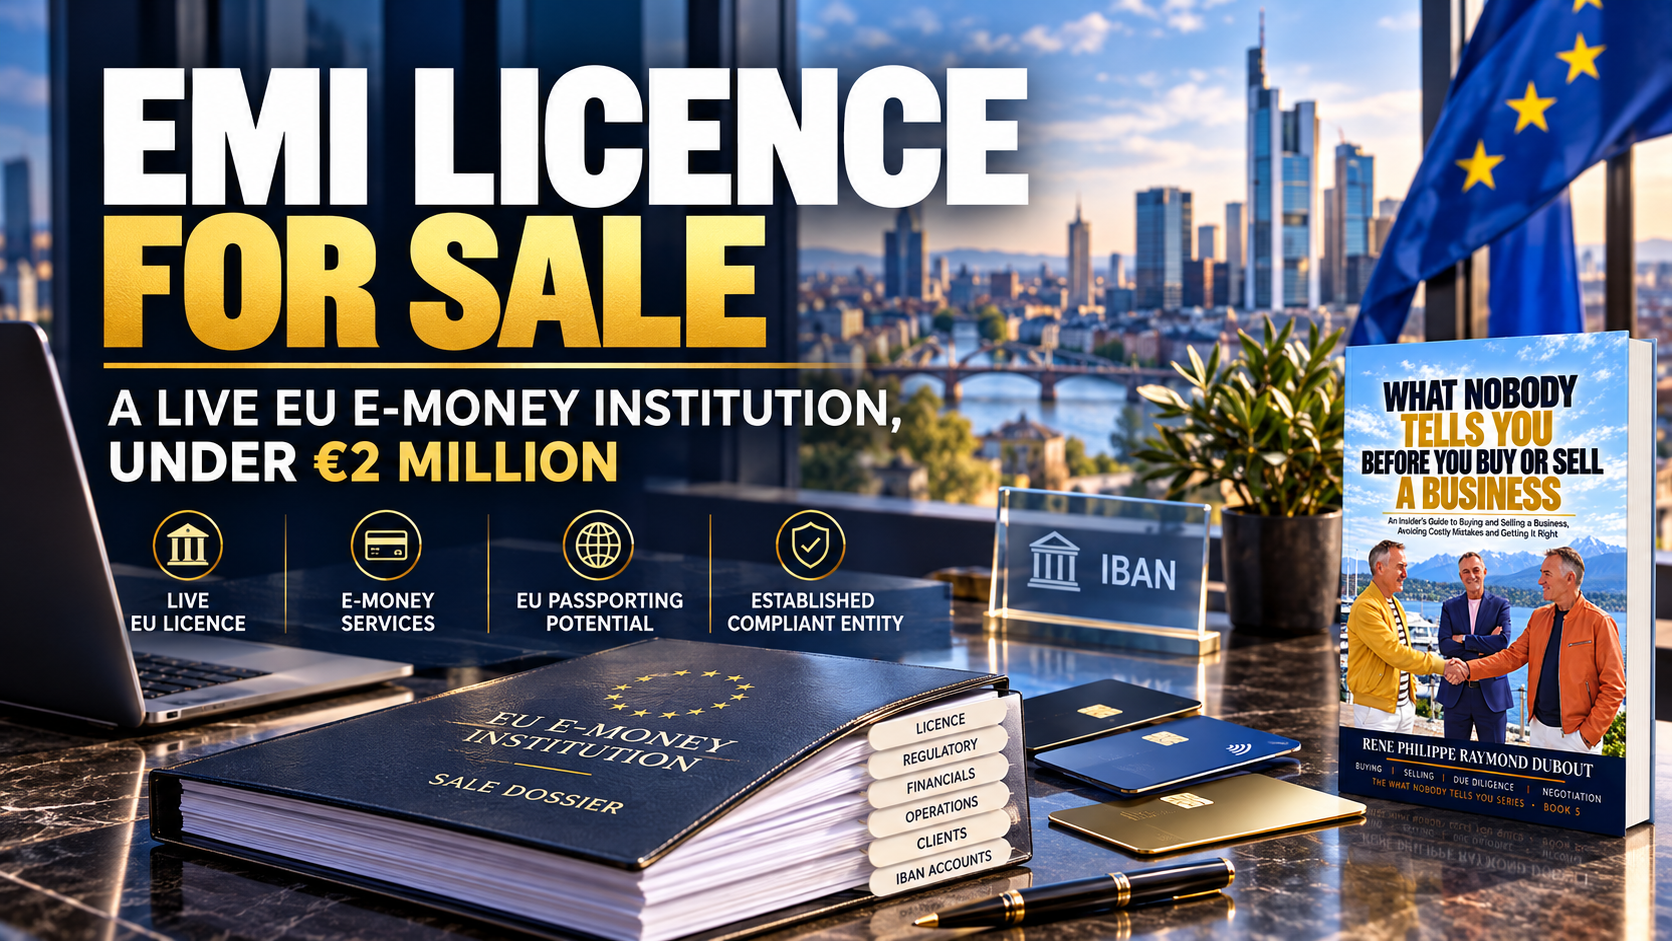
If you have shopped for an EMI licence for sale in the European Union lately, you know the menu. Option one: apply from scratch, wait, spend, and hope the regulator says yes at the end. Option two: buy an existing institution, and watch the asking price climb well past €2 million the moment it has anything that actually works.
This one is different. A licensed, operating Electronic Money Institution in Lithuania, with its payment rails, card programme, banking partners, customers and team in place. Asking price: under €2 million. Contact us for the exact price and terms.
In our experience, a working EU EMI with this level of infrastructure very rarely comes to market at that price. When it does, it does not stay there long.
What you are buying
- An EU e-money licence granted by the Bank of Lithuania, with access to the European Economic Area through passporting.
- Direct access to CENTROlink, the Bank of Lithuania’s payment system.
- A full card programme: active with international card schemes, prepaid card issuing, card loading, ATM withdrawals, and card acquiring through UK-based partners.
- International payments and FX: SWIFT transfers and currency exchange through a global payments provider.
- Safeguarding with licensed Lithuanian credit institutions, a core banking relationship with a major Lithuanian commercial bank, and a specialist AML platform.
- The key functions staffed: CEO, MLRO, Compliance, Risk and Operations.
In other words, the plumbing is done. And anyone who has built a payment institution knows the plumbing is the hard part.
The numbers that matter
- 2,558 customers on the books, 1,716 active, private and corporate.
- €56.5 million of payment volume over the last 12 months.
- Nine fee lines already billing: FX, card acquiring, transaction fees, interchange, transfers, deposit fees, card fees, account closure fees and corporate monthly fees.
This is not a licence on paper. Real money is moving through it today.
Who this is for
- Fintechs that want an EU licence of their own instead of renting someone else’s.
- Payment, FX and card businesses that need their own e-money licence to scale in Europe.
- Groups outside the EU looking for a regulated entry point into the European market.
- Existing institutions that want to add customers, rails and a card programme in one move.
How the process works
- Expression of interest: a short buyer profile and your intended use of the licence. We then share the price and terms.
- NDA and data room: full financials, partner agreements and compliance documentation.
- Offer and due diligence: indicative offer, then full legal and regulatory review.
- Regulatory approval: the change of control is approved by the Bank of Lithuania before closing.
FintechLex handles the sale of regulated financial entities across Europe and Asia, from the first call to the change-of-control filing and the activation after closing. We know what regulators ask, and we know where deals get stuck.
Interested? Contact us for the price and the confidential teaser: insight@fintechlex.com
Information provided by the company, unaudited. This post is not an offer; all details are subject to due diligence and regulatory approval.