Crypto Custody and Staking in Switzerland: Is SRO Enough, and When You Need a FINMA Licence.
Holding crypto for clients is one of the most common business models we see in Switzerland, and one of the most misunderstood. The same wallet app can need only an SRO membership, a FinTech licence, or a full banking licence. The difference is not the technology. It is who controls the coins, how they are booked, and what you do with them.
This guide sets out where the lines are today, and what is coming. It is part of our Swiss crypto licence guide.
Three questions decide the licence
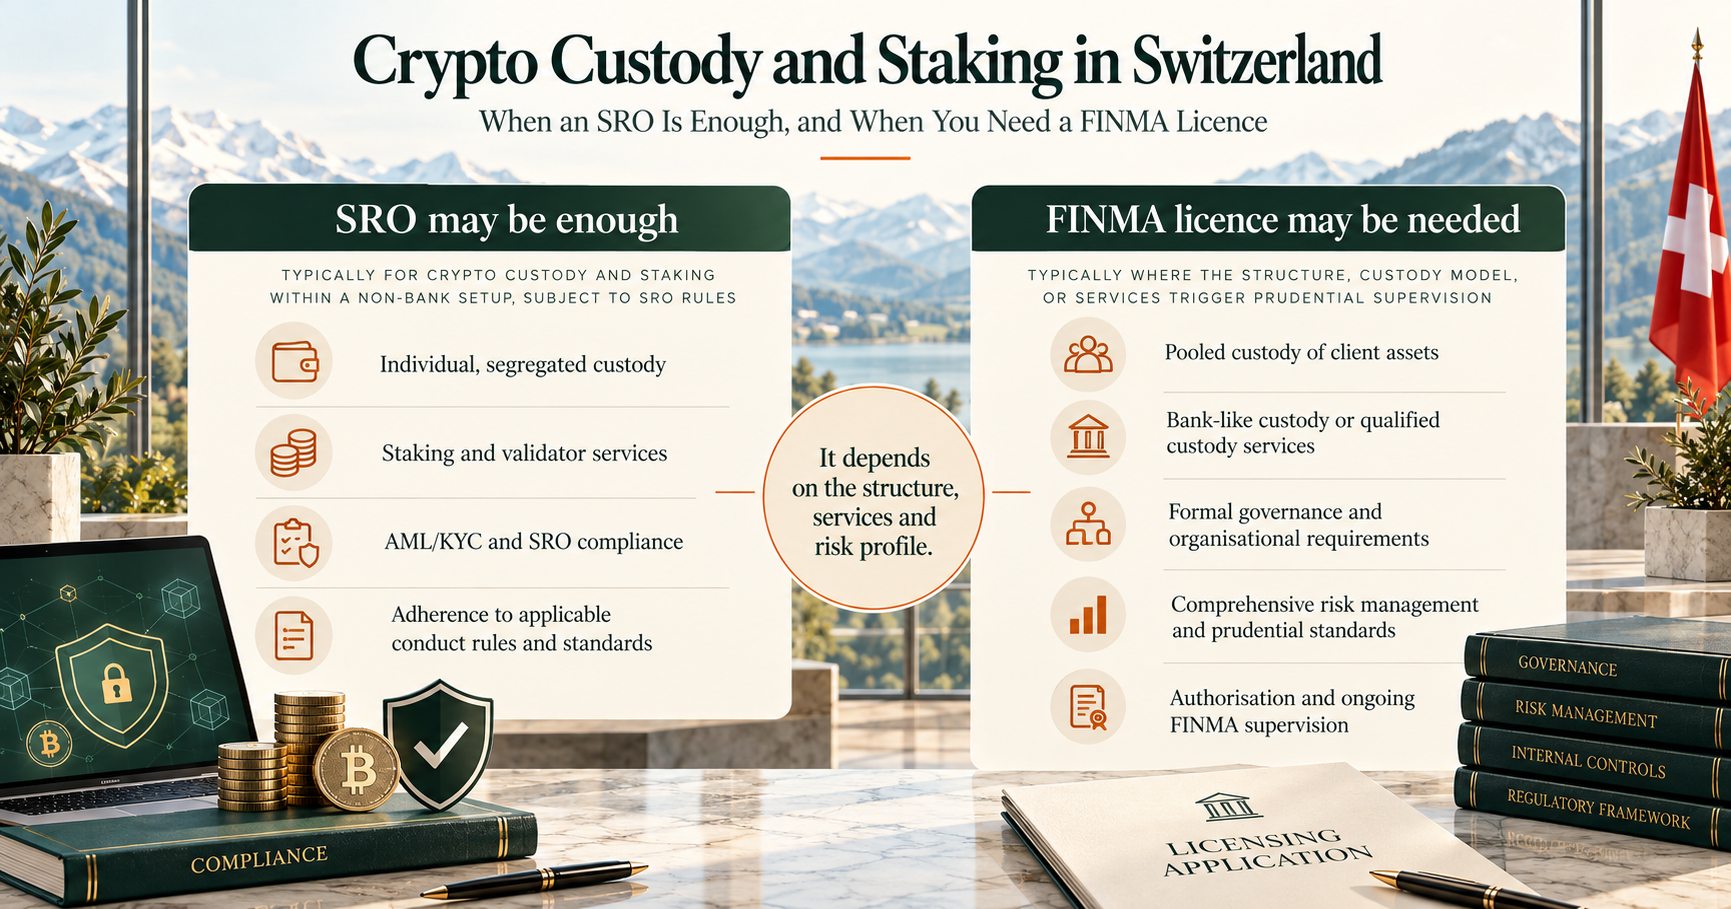
- Who controls the assets? If the client alone controls the private keys, the provider may simply be supplying software. If the provider can dispose of client assets, AML obligations generally arise.
- How are the assets held? Individual custody can operate under SRO supervision. Collective custody of payment tokens generally requires a FINMA licence, even where each client’s share is clearly recorded.
- What can the provider do with the assets? Safekeeping is one thing. Lending, using client assets for the provider’s own business or offering staking services can change the regulatory classification.
Segregated custody: SRO membership
Individual custody does not normally require a banking licence, provided the assets remain identifiable, are held in readiness for the client and meet the conditions for segregation in bankruptcy.
The custodian must nevertheless comply with Swiss anti-money laundering requirements and, unless subject to another appropriate form of AML supervision (for example as a bank or securities firm supervised by FINMA), affiliate with a recognised SRO. This involves client identification, verification of beneficial ownership, transaction monitoring, record-keeping and periodic AML audits. Audit frequency depends on the applicable SRO rules and the company’s risk profile. See The Swiss SRO Annual Audit.
An SRO membership is AML supervision. It is not a FINMA banking or prudential licence.
Pooled custody: FinTech or banking licence
Pooling client cryptocurrencies in a single omnibus wallet changes the regulatory position.
Under Swiss banking law, the commercial collective custody of crypto-based payment assets generally requires a FINMA authorisation, even where an internal ledger identifies each client’s entitlement.
If each client’s share is clearly recorded and the assets remain available for clients, a FinTech licence under Article 1b of the Banking Act may be sufficient. Where client shares cannot be clearly identified, or the assets are not kept available, a full banking licence may be required.
The CHF 100 million limit applicable to the FinTech licence concerns public deposits. It should not be presented as a general ceiling on segregable crypto-based assets held in collective custody.
The precise structure matters. A good internal ledger is necessary, but it does not turn collective custody into individual custody.
Using the coins: where banking law starts
The position changes when a custodian starts using client assets for its own business.
Lending out client cryptocurrencies, re-pledging them for the custodian’s own obligations or using them for proprietary activities can prevent the assets from qualifying as bankruptcy-protected custody assets. Depending on the structure, they may instead be treated as public deposits, triggering banking-law authorisation and capital requirements. See Deposit or E-Money? What Happens to Your Money If Your Fintech Fails.
However, not every form of staking automatically turns client assets into deposits. Staking carried out specifically for a client, under conditions recognised by FINMA, must be distinguished from staking undertaken for the custodian’s own account.
The question is not simply whether the client receives a return. It is who controls the assets, who bears the risks and whether the client retains an enforceable right to identifiable assets.
Staking: how it can operate without a banking licence
The Staking deserves particular attention because the legal treatment depends on how the service operates.
This is why staking is often confused with traditional banking because both can generate returns for clients. Legally and economically, however, they are very different activities.
1. Staking is not traditional deposit-taking
A bank generally uses deposits as part of its lending and financing activities. In proof-of-stake networks such as Ethereum, Cardano or Polkadot, staking rewards arise from participation in securing and operating the blockchain.
These rewards can include newly issued tokens and network transaction fees. They are not necessarily interest paid by borrowers.
Consequently, providing a staking service does not, by itself, constitute banking or deposit-taking.
2. What FINMA accepts
FINMA distinguishes between non-custodial staking, custodial direct staking and arrangements involving other staking providers.
Under its Guidance 08/2023, an SRO-supervised provider may carry out certain forms of direct staking on behalf of clients without a banking licence, provided the conditions for individual custody are respected. These include separate, identifiable addresses and the provider retaining the relevant withdrawal keys.
The position becomes more complicated when assets from several clients are pooled, when another provider controls the withdrawal keys or when the custodian uses the assets for its own account.
Lock-up periods and slashing also create uncertainty about bankruptcy protection. FINMA’s supervisory approach contains specific conditions and does not amount to a general exemption for staking businesses.
3. Bitcoin Suisse: a practical example
Bitcoin Suisse illustrates how institutional crypto custody and staking can operate outside a traditional banking licence.
In Switzerland, Bitcoin Suisse AG operates as a financial intermediary affiliated with VQF, a self-regulatory organisation recognised by FINMA.
Its European subsidiary, Bitcoin Suisse (Europe) AG, received authorisation from the Liechtenstein Financial Market Authority in June 2026 to provide crypto-asset services under MiCAR, including custody and administration of crypto-assets on behalf of clients.
Neither SRO membership nor a CASP authorisation should be confused with a banking licence.
Under MiCAR, staking does not constitute a separately licensed activity. However, staking services involving custody of client assets must comply with the applicable CASP custody requirements.
4. Custody and validator infrastructure
Bitcoin Suisse operates institutional custody infrastructure and validator services for proof-of-stake networks.
In Switzerland, depending on the custody product and operational requirements, client assets may be held in individually segregated custody arrangements or temporarily in collective custody. The latter arrangements are subject to specific contractual and regulatory safeguards, including applicable bank guarantee provisions.
A distinction must also be made between validator signing keys, which are used to operate the blockchain validator, and withdrawal credentials, which determine control over the staked assets.
The legal treatment depends on the contractual arrangements, asset segregation, control of withdrawal rights and whether the provider can use the assets for its own purposes.
Where these arrangements satisfy the applicable regulatory and bankruptcy-law requirements, staking can be provided without a traditional banking licence.
5. Client protection is different from bank deposit insurance
Cryptoassets held in qualifying segregated custody arrangements may be protected from the custodian’s bankruptcy estate.
That protection is not equivalent to bank deposit insurance. It does not eliminate market risk, slashing risk, technical failures, withdrawal delays or all counterparty risks.
The important question is therefore not simply whether staking pays a return, but how the client’s assets are legally held, controlled and protected.
Key distinctions
| Feature | Traditional banking | Crypto staking services |
|---|---|---|
| Source of return | Lending and other banking activities | Blockchain protocol rewards |
| Regulatory framework | Banking legislation | AML, custody rules and potentially banking legislation |
| Required authorisation | Banking licence for regulated deposit-taking | Depends on jurisdiction and business structure |
| Asset treatment | Deposits generally constitute claims against the bank | Qualifying custody assets may be segregated |
| Client protection | Applicable deposit protection and banking safeguards | Custody segregation, legal rights and operational safeguards |
| Main risks | Credit, liquidity and bank insolvency | Slashing, technical, custody, counterparty and market risks |
At a glance
| Business model | Typical regulatory position |
|---|---|
| Non-custodial wallet software, client retains exclusive control | Normally no custody licence or SRO for custody alone |
| Individual custody, separate client addresses | Generally SRO supervision |
| Collective custody, clear client entitlements, assets kept available | FinTech licence or banking licence |
| Collective custody, client entitlements not clearly identifiable | Banking licence |
| Direct client staking under FINMA’s specified conditions | SRO may be sufficient |
| Lending or proprietary use of client assets | Banking-law assessment; banking licence may be required |
The regulatory outcome always depends on the actual business model, not simply the name given to the service.
For licensed institutions: FINMA Guidance 01/2026
On 12 January 2026, FINMA set out its expectations for the custody of crypto-based assets by the institutions it supervises: banks, portfolio managers, fund managers and issuers of crypto products. The key points:
- Custody abroad is possible only with a sub-custodian under equivalent supervision, in a country whose bankruptcy law protects the assets.
- The Swiss institution stays responsible, even when custody is outsourced.
- A portfolio manager that keeps an existing SRO-only custodian must inform clients of the higher risk, show them alternatives and obtain their written consent.
For SRO-only custodians, the message is clear: regulated clients will ask for more than an SRO membership.
What is coming: the crypto institution
Switzerland is preparing a further regulatory reform.
In October 2025, the Federal Council launched a consultation on amendments to the Financial Institutions Act, proposing two new categories: payment instrument institutions, intended to replace the existing FinTech licence, and crypto-institutions.
The proposed crypto-institution framework would cover various professional services involving cryptoassets, including relevant custody and trading activities.
The consultation closed on 6 February 2026. The proposals are not yet a substitute for the current licensing framework, and their final scope, transitional arrangements and implementation date will depend on the legislative process.
For businesses planning to offer custody services in Switzerland, the sensible approach is to understand the current requirements while preparing for a potentially more demanding regulatory environment. On stablecoins, see Issuing a Stablecoin in Switzerland.
Ask us where your custody model falls, or write to insight@fintechlex.com.
This article is for general information only and does not constitute legal advice.
Crypto Custody and Staking in Switzerland: When an SRO Is Enough, and When You Need a FINMA Licence