What does a buyer really want when he looks for a payment company? Not a licence in a drawer with a nice certificate and nothing behind it. He wants a licence that works, technology that runs, customers who pay and a team that knows the job. That combination is rare on the market. FintechLex is currently presenting one.
What is on the table
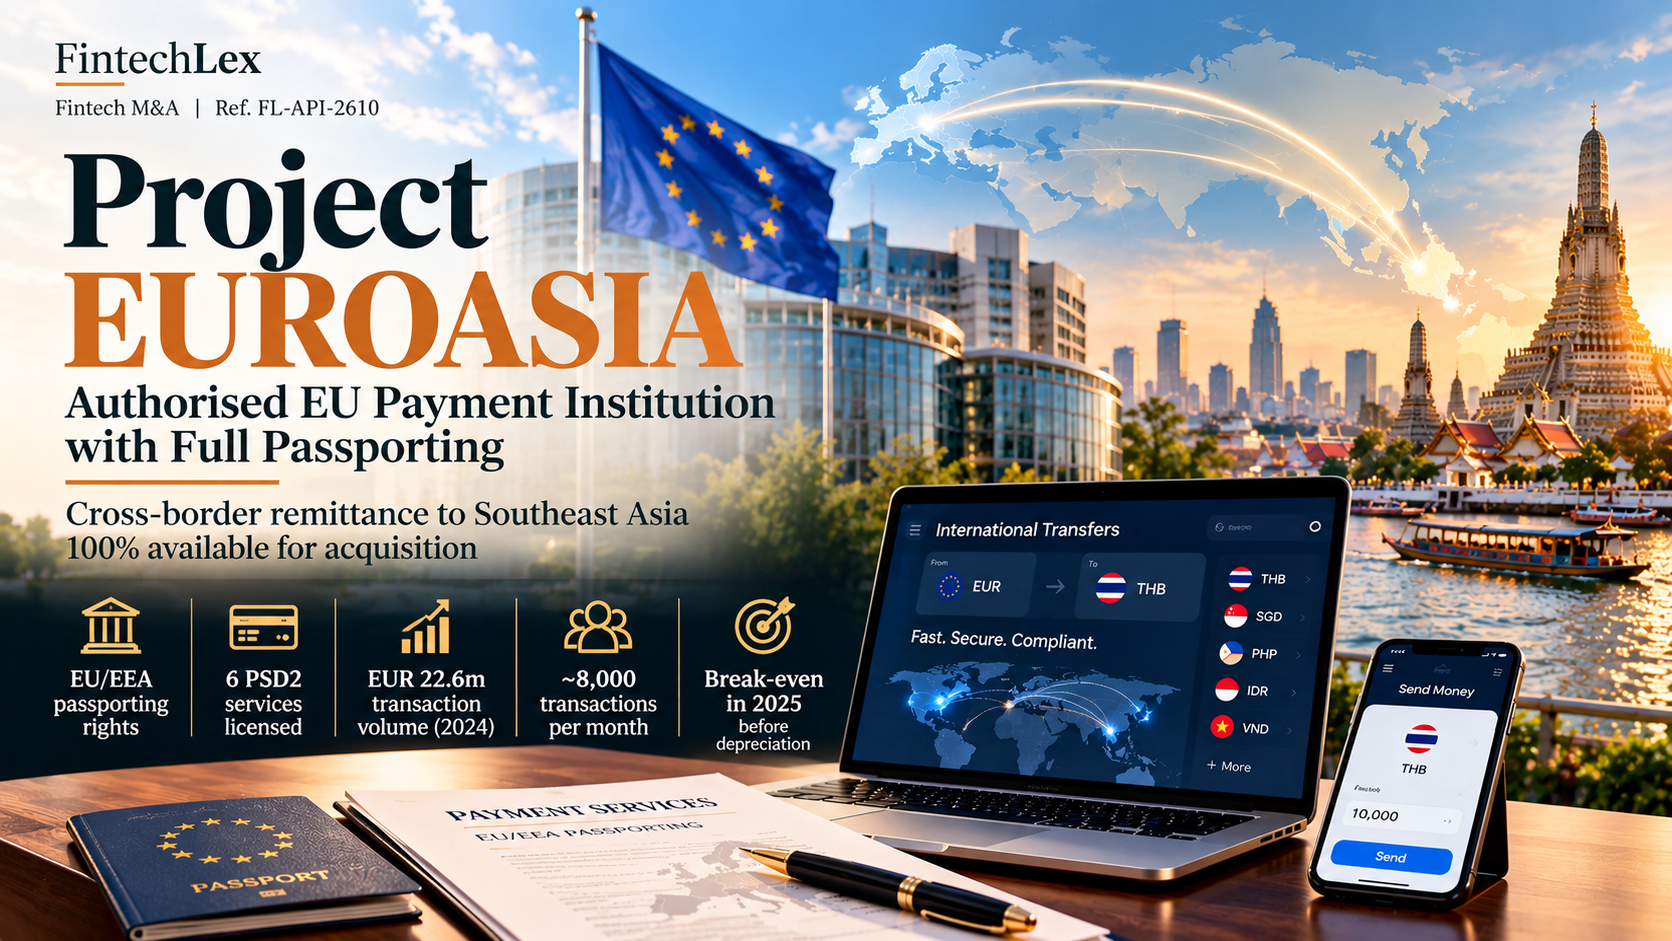
100% of a fully licensed European payment institution, operating since 2019 and based in Northern Europe. Its business is cross-border remittance, with a strategic focus on Southeast Asia. It operates under PSD2 with EU/EEA passporting rights and is already active in three European sending markets.
The licence is broad. It covers a wide range of PSD2 payment services:
- Money remittance
- Execution of payment transactions: credit transfers, standing orders, card-based payments and direct debits
- Issuing of payment instruments
- Acquiring of payment transactions
- Payment initiation services
- Account information services
The numbers
The company is fully operating. Annual transaction volume is above EUR 20 million, it processes thousands of transactions every month, and it has reached break-even.
Here is the detail that matters: it got there with a single payout country, Thailand. Further European expansion is planned, along with 11 Asian markets and potential access to more than 140 payout countries. A new brand for Europe is ready for launch.
In other words, the hard and expensive part (licence, platform, compliance, first corridor) is done and paid for. Each new corridor plugs into what already exists. That is where a buyer makes his return.
The technology belongs to the company
This point is often overlooked. Many small payment institutions rent their platform and are at the mercy of their supplier. This one runs on a proprietary platform built in-house, with about 15 integrations (card payments, open banking, KYC, sanctions screening, FX and international payout networks) and its own iOS and Android apps. There is no platform to rebuild before you grow.
Who should look at it
- Remittance and money-transfer operators that want an EU licence with an Asian corridor already live
- Asian payment and remittance groups looking for a regulated, passported way into Europe
- Fintech platforms and neobanks that want to own their payment rails rather than rent them
- Investors looking for a licensed platform at break-even with clear growth ahead
The trap nobody mentions
A licence does not change hands like a car key. The regulator must approve the new owner, and it will look closely at your shareholders, your source of funds, your management and your plan. Buyers who underestimate this lose months. Our job at FintechLex is to prepare that file properly and take the deal from first review to closing.
How to go further
Detailed figures, company identity, jurisdiction, audited 2025 accounts and terms are released after signature of a non-disclosure agreement. Prices are on request.
Email: insight@fintechlex.com
WhatsApp: +41 787 983 770