Yes. But there is a catch, and it can cost you the licence.
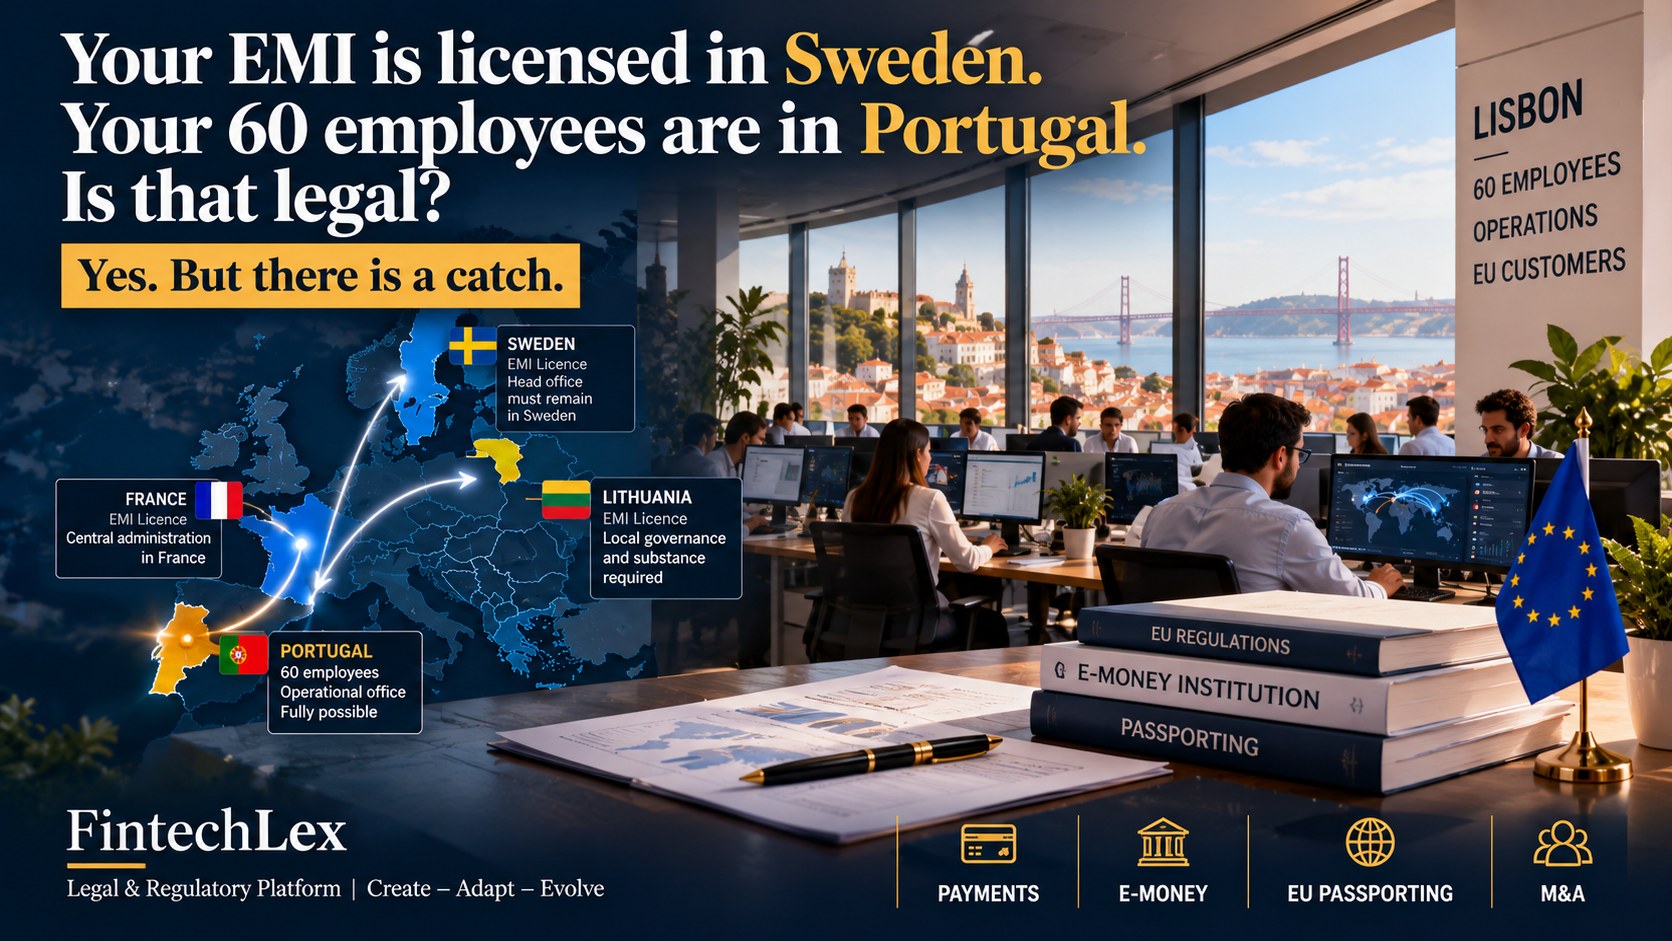
Imagine you buy an electronic money institution (EMI) licensed in Sweden, France or Lithuania. You want to serve customers across the European Union, and you want to run the business from Lisbon, with 60 people. The weather is better, salaries are lower and the talent pool is deep. Can you do it?
Yes. EU passporting allows an authorised EMI to open branches and provide services across the EU, once the required notifications are made. But passporting does not let you take a licence in one country and quietly run the institution from another.
The rule starts in Europe, but every country writes it its own way
The starting point is European. Article 11(3) of PSD2, which applies to EMIs through the E-Money Directive, requires two things:
- the head office must be in the same country as the registered office, and
- the institution must carry out at least part of its business there.
But a directive is never copied word for word. Each country writes it into its own law in its own terms, sometimes adds requirements, and each regulator has its own reading of what a “real” head office is. The same principle can mean a few local directors in one country and a full management team on site in another. That is why the country of the licence matters as much as the licence itself.
Three countries, three styles
🇸🇪 Sweden. Swedish law spells it out: the head office of an EMI must be in Sweden. Sixty operational staff in Portugal are fine. A head office in Sweden that exists only on the letterhead is not.
🇫🇷 France. The central administration must sit in France, where the registered office is, and part of the e-money business must be done in France. A large branch in Lisbon is possible. Moving the real central administration to Lisbon while keeping the French licence is another matter.
🇱🇹 Lithuania. The Bank of Lithuania wants a registered office and a credible governance and operating structure in Lithuania. It checks whether the institution can genuinely manage its activities, its risks and its internal controls from there. A 60-person team in Portugal may be perfectly acceptable. An empty Lithuanian shell that controls nothing is not.
Where it gets interesting
Suppose your EMI has 60 employees in Lisbon and three people in the licensing country. That is not illegal in itself.
But suppose the CEO, the CFO, compliance, risk management and every important decision are in Portugal. Then you have a serious problem. The regulator does not count heads. It asks where the institution is actually managed and controlled. If the answer is “somewhere else”, the next questions can lead to remediation orders and, in the worst case, withdrawal of the licence.
What this means when you buy an EMI
Buyers usually look at three things: the licence, the capital and the customer portfolio. Look at a fourth: where the company is really run, and where you plan to run it after closing. The regulator will see your reorganisation plan in the change-of-control file. If your plan is to move everything to Lisbon and leave a letterbox behind, it is better to know before you sign than after.
An EU passport lets you cross borders. It doesn’t let you leave your regulator behind.
Buying an EMI?
FintechLex has licensed EMIs and payment institutions for sale in the EU and the UK. We check more than the licence: governance, substance and whether your post-closing plans will survive the regulator. Write to us at insight@fintechlex.com or on WhatsApp +41 787 983 770.
Rene-Philippe