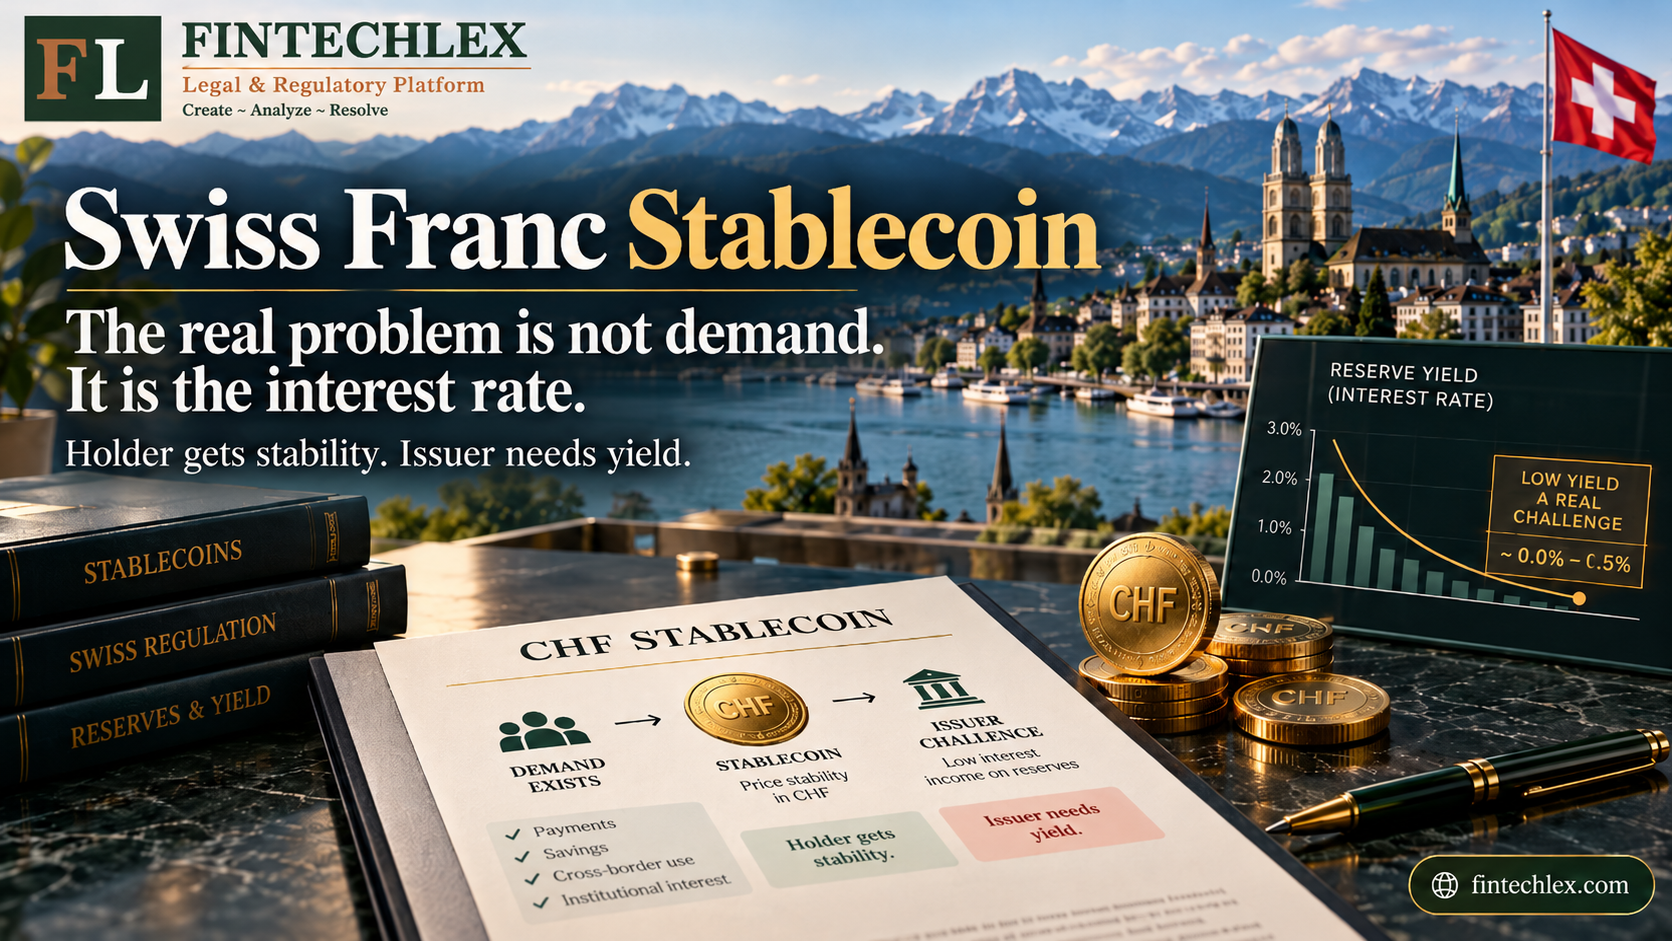
A Swiss franc stablecoin sounds like an easy sell. The franc is one of the world’s favourite safe havens, and people already pay a premium to hold it. Put it on-chain, with a proper Swiss licence behind it, and the buyers should line up.
I thought so too, until a conversation this week with a fellow crypto lawyer on LinkedIn. He put his finger on the real problem, and it is not demand. It is the interest rate.
1. How a stablecoin issuer actually makes money
A stablecoin issuer takes your money, gives you a coin, and promises to buy the coin back at par. In between, it holds a reserve. Its main income is the interest earned on that reserve.
It cannot share that interest with you. Under the Swiss draft, a payment instrument institution may accept client funds only if it pays no interest on them (draft Article 51a). It must keep the reserve in sight deposits with a bank, or in high-quality liquid assets with short maturities (draft Article 51i). It may keep the investment income for itself (draft Article 51k).
So the model is simple: the holder gets stability, the issuer gets the yield. The whole business stands on the yield. For the rules behind the new licence, see Stablecoin Licence Switzerland.
2. The franc problem: zero
On 24 September 2026, the Swiss National Bank (SNB) left its policy rate at 0%. Its inflation forecast assumes the rate stays there. SARON, the overnight rate for Swiss francs, sat slightly below zero in October 2026.
On 16 September 2026, the US Federal Reserve raised its target range to 3.75%–4%. The same reserve, in dollars, earns real money.
Take a reserve of 100 million, held in short-term, high-quality assets:
| Dollar stablecoin | Swiss franc stablecoin | |
|---|---|---|
| Reserve | USD 100 million | CHF 100 million |
| Short-term rate (October 2026) | About 3.75% to 4% | About 0%, slightly negative overnight |
| Yearly income for the issuer | Roughly USD 3.8 million | Close to nothing |
| Who pays the compliance team, the audit and the custodian bank? | The reserve | Nobody, unless the issuer charges fees |
The dollar issuer is paid by the Federal Reserve. The franc issuer is paid by nobody. And the costs are the same on both sides: capital, a compliance team, an external audit, a custodian bank, technology, reporting. The safe-haven status attracts holders. It does not pay the issuer.
3. It can get worse: negative rates
Zero is not the floor. From January 2015 to September 2022, the SNB policy rate was negative, at -0.75% for most of that period.
The Swiss draft has thought about this. According to the explanatory report, negative interest charged on the reserve may be passed on to the holders: the reserve shrinks, and the number of coins shrinks with it, while each coin is still redeemed at one franc. It protects the issuer. But try selling a coin whose balance gets smaller every month.
Two more rules make the reserve expensive. It must be held in the same currency as the coin: a franc coin needs franc assets, so no dollar Treasuries hedged back into francs. And the report expects a buffer above 1:1 in most cases, to absorb market risk on the reserve. That buffer is the issuer’s own money, also earning nothing.
4. Who can make it work
The economics do not make a franc stablecoin impossible. They decide who can afford one.
- Banks and banking consortia, for whom the coin is a payments tool, not a profit centre. In April 2026, UBS, PostFinance, Sygnum, Raiffeisen, Zürcher Kantonalbank and BCV announced a Swiss franc stablecoin sandbox, run in 2026 with a limited participant pool and transaction limits. For them, the question is not the yield; it is keeping the payments business in Swiss hands. But banks have a problem of their own, explained below.
- Issuers that charge for the service: issuance and redemption fees, transaction fees, or a fee paid by the businesses that use the coin. It works, but it is a harder sell than a free coin. Swiss rules may also allow what European rules forbid: under MiCA, an e-money token must be redeemed free of charge, at any time, while the Swiss draft leaves redemption terms, including possible fees, to the Federal Council. For institutional users who value speed and settlement around the clock, a modest fee on issuance and redemption is a cost of doing business, not a deal-breaker.
- Issuers with an ecosystem around the coin: an exchange, a payments platform or a trading business that earns its money elsewhere and uses the coin to bring flows in.
- Issuers that need funding would love a franc coin: it is money at zero cost. But the Swiss draft closes that door for payment instrument institutions: the reserve must sit in bank deposits or short-term liquid assets, not in the issuer’s own projects.
Why banks have a problem of their own. Under the Swiss draft, a bank cannot issue a Swiss stablecoin itself. No other licence covers the activity of a payment instrument institution, not even a banking licence, so a bank must set up a separate legal entity (explanatory report, page 51). That changes the economics in three ways:
- The subsidiary lives on the same zero. It is bound by the same reserve rules as any other issuer: bank sight deposits or short-term liquid assets, in the same currency, with no interest for the holders. The bank cannot use the money it receives to fund its loans, which is exactly how a bank makes money.
- The fixed costs double. The subsidiary needs its own capital, governance, compliance team and audit. At 0%, those are costs with no income against them. A banking group can carry them, but only if it sees the coin as a strategic tool to defend its payments business, not as a profit centre.
- Tokenised deposits look more attractive. A tokenised deposit stays on the bank’s balance sheet: the bank can lend it, and it remains a bank deposit, with the usual depositor protection. No subsidiary, no new licence. The explanatory report treats tokenised deposits separately from stablecoins. Many banks may therefore end up preferring them.
The banks’ announcement speaks of a Swiss franc stablecoin, but does not say how it would be issued. Whether the sandbox ends in a stablecoin issued by a subsidiary, or in tokenised deposits, will tell us how the banks have done the arithmetic.
What does not work is the dollar model copied into francs: a stand-alone issuer, living on its reserve income. At 0%, that issuer runs at a loss from the first day.
5. The foreign route
Franc stablecoins will not only come from Switzerland. In February 2026, AllUnity, a joint venture of DWS, Flow Traders and Galaxy, announced CHFAU, a franc-denominated e-money token under the European MiCA rules.
Under the Swiss draft, a coin like this is a foreign stablecoin: it counts as a crypto-asset with trading character. A Swiss firm that holds or trades it for clients will need the new crypto institution licence. We explain the difference between Swiss and foreign stablecoins in Switzerland vs the EU: Which Swiss Licence Matches Which European Licence?.
The foreign issuer faces the same arithmetic, with one difference: if its group earns money elsewhere, it can carry a franc coin at a loss as part of a wider offer. A stand-alone Swiss issuer cannot.
6. The workarounds: what works and what does not
Ask around and you will hear a dozen clever fixes. Here is how they hold up against the Swiss draft:
| Idea | Does it work in Switzerland? |
|---|---|
| Minting, redemption and transaction fees | Yes. Legal and simple. The only question is whether users will pay. |
| Settlement coin for banks, wealth managers and exporters, paid per transaction | Yes. Probably the most realistic model: the coin earns its keep as infrastructure. |
| Coin inside a wider business (exchange, payments platform) | Yes, if the rest of the business pays for it. |
| Higher-yield reserve assets (corporate paper, covered bonds) | Very limited. The reserve must sit in bank sight deposits or high-quality liquid assets with short maturities. A few basis points at best. |
| Dollar reserves hedged back into francs | No. The reserve must be in the currency of the coin. And the hedge would cost roughly the rate difference anyway. |
| Over-collateralised basket of Swiss shares or real estate | No. That is no longer a stablecoin under the new licence, but a fund or a security, with its own rules. |
| Passing negative rates to holders | Allowed for negative interest on the reserve, but it only limits losses. It does not create income. |
| Bank guarantee instead of a licence (FINMA Guidance 06/2024) | Today, yes, at the price of the guarantee fee. After the reform, issuing a single-currency stablecoin requires the payment instrument institution licence. |
| A bank tokenising its own deposits | Yes, for a bank. Tokenised deposits stay bank deposits that the bank can lend. But that is a deposit token, not a stablecoin under the new licence. |
The pattern is clear. Everything that tries to squeeze more yield out of the reserve runs into the reserve rules. Everything that works earns its money from the service, not from the float.
Three of the models that work deserve a closer look:
- A bank partner that pays for the business you bring. The reserve sits in bank deposits. A bank still earns money lending francs, even at a 0% policy rate, so it may pay something for the deposits, the customers and the payment or foreign exchange flows. Not much, though: deposits that can leave in a day of mass redemptions are expensive for a bank to hold, and it will price that in.
- Shared infrastructure. Several institutions carry the costs together. This one deserves a chapter of its own: see below.
- Foreign exchange. A convenient way in and out of francs is worth a margin on every conversion, even when holding francs earns nothing.
The arithmetic is unforgiving. Take a reserve of CHF 100 million, running costs of CHF 2 million a year, and a net margin of 0.05% on paid transaction volume. These are planning assumptions, not market prices:
| Return on the reserve | Reserve income | Revenue still needed | Paid transaction volume needed per year |
|---|---|---|---|
| +0.50% | +CHF 0.5 million | CHF 1.5 million | CHF 3 billion |
| 0% | Nothing | CHF 2 million | CHF 4 billion |
| -0.50%, borne by the issuer | -CHF 0.5 million | CHF 2.5 million | CHF 5 billion |
Passing negative rates on to holders brings the last line back to the middle one. Subscriptions and minimum fees reduce the volume needed. Either way, a franc stablecoin lives on volume and paying customers, not on the size of its reserve.
7. No solution? Look at what Switzerland has already built
So far, the picture is grim. The reserve earns nothing. The cleverer ideas run into the reserve rules. And a bank that wants its own coin needs a separately licensed company, with its own capital and costs, and a reserve it cannot lend.
Now picture six banks each doing it. Six licences, six compliance teams, six audits, six coins competing for the same small market, and not one of them profitable. That is not a market. That is six cost centres.
Unless they build it together.
Switzerland has met this problem before: infrastructure that everyone needs, that nobody can justify alone, and that only works if everybody uses the same one. Twice, the answer was the same.
- SIX. The company behind the Swiss stock exchange and much of the country’s payment infrastructure is owned by around 120 Swiss and foreign financial institutions, which are also its main users. No single shareholder controls it.
- TWINT. When the Swiss payment app took its current shape in 2016, its shareholders were UBS, Credit Suisse, Raiffeisen, Zürcher Kantonalbank, PostFinance and BCV, together with SIX. Competitors in banking, partners in infrastructure. Today it is how Switzerland pays with its phone.
Now look again at who announced a Swiss franc stablecoin sandbox in April 2026: UBS, PostFinance, Sygnum, Raiffeisen, Zürcher Kantonalbank and BCV. Five of the six were already around the TWINT table.
They have done it before. Why not for a stablecoin?
A jointly owned payment instrument institution would turn every weakness of the franc stablecoin into something the banks can live with:
| The problem | The consortium answer |
|---|---|
| The reserve earns nothing | The venture lives on membership and usage fees paid by its owners and their clients. Interest income, if rates rise, is a bonus, not the plan. |
| A bank needs a separate licensed company | One company, outside every bank’s balance sheet, exactly as the Swiss draft requires. Common ownership is no obstacle. |
| Fixed costs for capital, compliance and audit | Paid once, shared by all. Each bank pays a fraction of what its own subsidiary would cost. |
| Volume is what pays the bills | One coin for the whole Swiss market, instead of six coins splitting the same flows. |
| Small players cannot afford a licence | Open access for other banks and fintechs on equal terms, as with TWINT and SIX. |
The revenue would come from what the owners and their clients actually pay for: membership, settlement between institutions, issuance and redemption fees where the Swiss rules allow them, and foreign exchange in and out of francs. None of it depends on the Swiss National Bank.
It is not without risk. Consortia can die in committee, so the venture needs a management team with a real mandate. Competitors building shared infrastructure must keep it open and neutral, which competition law will watch. Some banks will still prefer to tokenise their own deposits. And the rules are still a draft. But the model is proven, the shareholders already know each other, and the arithmetic finally works.
8. What this means if you plan a franc stablecoin
- Build the business plan on fees and flows, not on the float. If the plan only works when the SNB raises rates, it is a bet on monetary policy, not a business.
- Price in negative rates. Model what happens if the SNB goes back below zero for several years, as it did from 2015 to 2022, and whether your users will accept a shrinking balance.
- Know your size. Fixed costs do not shrink with the reserve. At 0%, size alone does not save you; volume of paid transactions does.
- Think about who carries the coin. A bank, an exchange or a payments group can carry a franc coin as a service. A stand-alone start-up needs paying users from day one.
The demand for a franc stablecoin is real. The money to run it has to come from somewhere other than the reserve, and the most Swiss answer may be the oldest one: build it together. Planning a stablecoin, or the licence behind it? Write to insight@fintechlex.com.
Read the full series on the new licences and stablecoins:
- Switzerland’s Two New Licences: What Goes to the Payment Licence, What Goes to the Crypto Licence, and What Is Left for the SRO
- EMI, MiCA and Stablecoin Licences in Europe: Three Regimes, and What PSD3 Changes
- Switzerland vs the EU: Which Swiss Licence Matches Which European Licence?
- Stablecoins: When Even a Bank Needs a Separately Licensed Subsidiary
Sources: SNB monetary policy assessment of 24 September 2026; SARON data for October 2026; US Federal Reserve decision of 16 September 2026; Federal Council consultation draft of 22 October 2025 amending the Financial Institutions Act (Articles 51a, 51i, 51k) and its explanatory report; UBS media release of 8 April 2026; SIX Group ownership structure; BCV media release of 2016 on TWINT; AllUnity announcement of 2 February 2026. Figures in the table are rounded and for illustration. General information, not legal advice.