Every second fintech founder I meet this year wants to issue a stablecoin. Their own coin, their own name on it, their own reserve. It sounds like the big prize.
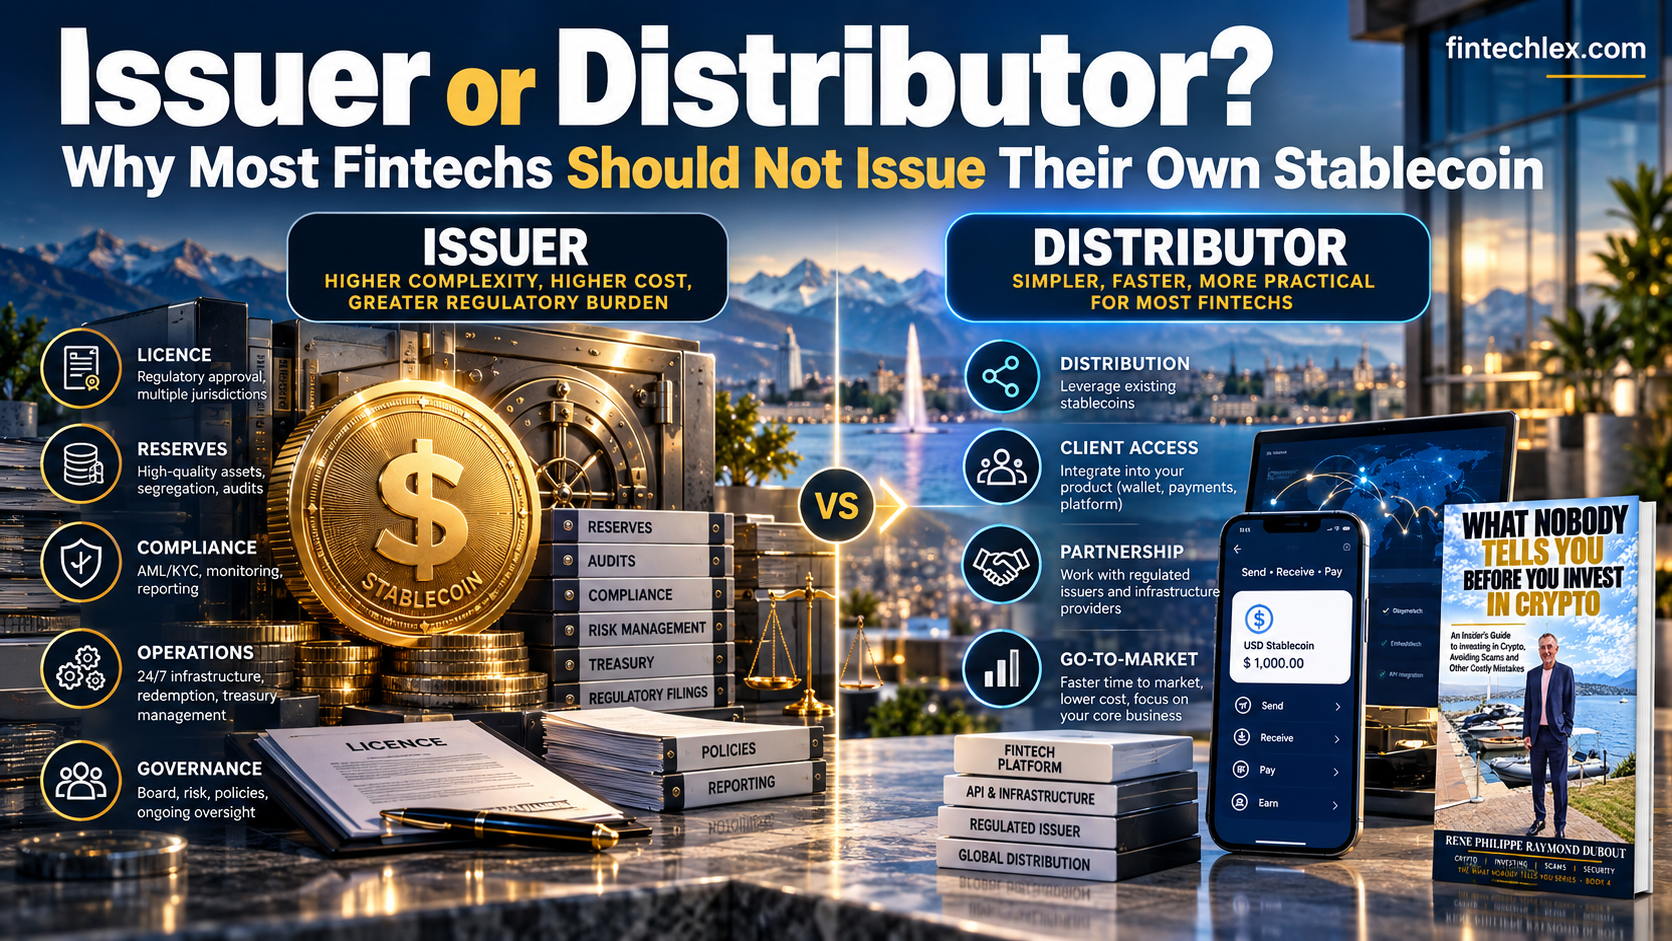
For most of them, it is the wrong prize. Before you decide to issue a stablecoin, ask a simpler question: do you want to be the issuer, or do you want to be the business that uses the coin? The money is usually in the second job. The burden is almost entirely in the first.
A bank to get in, a bank to get out
Look at how a fiat-backed stablecoin actually works. The client’s money comes in through a bank. The reserve sits with a bank or a custodian. When the client wants his money back, it goes out through a bank. The issuer sits in the middle.
So you have a bank to get in, a bank to get out, and one more fee layer in between: yours. Every one of those banks has to accept you as a client, review your compliance and decide that your coin is worth the risk. If one of them says no, your coin stops working, whatever your licence says.
What the issuer actually carries
Issuing is not a marketing decision. It is a regulated business, on both sides of the border:
- In Switzerland today, the money you receive for a currency-backed coin is in principle a public deposit. Without a banking licence, the usual route is a default guarantee from a Swiss bank, plus affiliation with an SRO, and every holder must be identified (FINMA Guidance 06/2024). We explain the details in Issuing a Stablecoin in Switzerland.
- In Switzerland tomorrow, under the draft reform, only a payment instrument institution licensed by FINMA could issue a Swiss stablecoin. Even a bank would need a separate subsidiary to do it. See Stablecoin Licence Switzerland.
- In the EU, a stablecoin tied to one currency is an e-money token under MiCA, and only an authorised bank or electronic money institution may issue it to the public.
- Everywhere: a reserve to manage and segregate, redemption on demand, a white paper, audits, and a compliance team that never goes home.
And the issuer carries the reputation risk. If the reserve is questioned, if a wallet is frozen, if a redemption is late, it is the issuer’s name in the press. Look at what Tether lives with every day: Your Stablecoin Is Global. Its Reserves Are Not.
Where the money is made
An issuer earns mainly one thing: the interest on its reserve. With dollar rates around 4%, a large dollar coin is a very good business. With the Swiss National Bank at 0%, a franc coin earns almost nothing on its reserve and still has to pay for everything above. We did the arithmetic in Why a Swiss Franc Stablecoin Is a Hard Business.
The business that uses the coin earns on something else: payment fees, exchange spreads, on- and off-ramp fees, merchant services, treasury services for corporate clients. Those revenues do not depend on the interest rate. They depend on the clients you have.
The best illustration is the biggest one. Circle issues USDC and carries the licences, the reserve and the audits. Coinbase distributes it, and earns a large share of the income on the USDC reserve through its agreement with Circle. One carries the burden. The other has the clients, and the clients are what the issuer pays for.
Distributing is not regulation-free either
Do not read this as “distribute and you need nothing”. If you exchange, transfer or hold stablecoins for clients, you are a financial intermediary. In Switzerland today, that means an SRO. Under the draft reform, trading or holding foreign stablecoins for clients would need the new crypto institution licence. In the EU, it means authorisation as a crypto-asset service provider under MiCA.
But that is a licence to serve clients, not a licence to create money. No reserve to defend, no redemption promise on your balance sheet, no bank guarantee to negotiate. You choose the coins you offer, and you can change them when the market or the regulator changes its mind, as EU platforms did with USDT this year.
When issuing does make sense
I am not saying nobody should issue. Some should:
- You already have the flow. A bank, an exchange or a payments group with its own clients can carry a coin as a service and spread the costs over an existing business.
- You serve a market nobody else serves. A currency or a use case with real demand and no licensed coin can justify the investment, if the rate environment pays for the reserve.
- You can afford the long road. Licence, capital, reserve management, banking partners on both ends, and two or three years before the coin is known enough to be used.
If you tick all three, issue. And put the coin in its own company, so that a hack or a run on the coin does not take the rest of your group down with it.
If you do not, start as a distributor. Build the clients, the flows and the compliance. If one day your volume justifies your own coin, you will issue it from a position of strength, with the clients already there. That is the right order.
What I tell clients
- Decide first what you want to earn on: the reserve, or the clients. Most fintechs should earn on the clients.
- If you issue, budget for the banks on both ends before you budget for the technology.
- If you distribute, choose licensed coins, and keep the option to switch.
- Either way, get the right status in the right country: an SRO or a FINMA licence in Switzerland, an electronic money institution or crypto-asset service provider in the EU. Applying takes time; buying an existing EU e-money institution or a Swiss SRO company can be faster.
Thinking about issuing a stablecoin, or about distributing one? Write to insight@fintechlex.com. We will tell you which side of the business you should be on.
Read the whole series: Stablecoins in Switzerland and the EU: The Complete FintechLex Guide.
Sources: FINMA Guidance 06/2024 on stablecoins; Federal Council consultation draft of 22 October 2025 amending the Financial Institutions Act; Regulation (EU) 2023/1114 (MiCA), Article 48; Circle and Coinbase public disclosures on their USDC arrangement. General information, not legal advice.